Actively Managed Versus Robo Advisors Compared
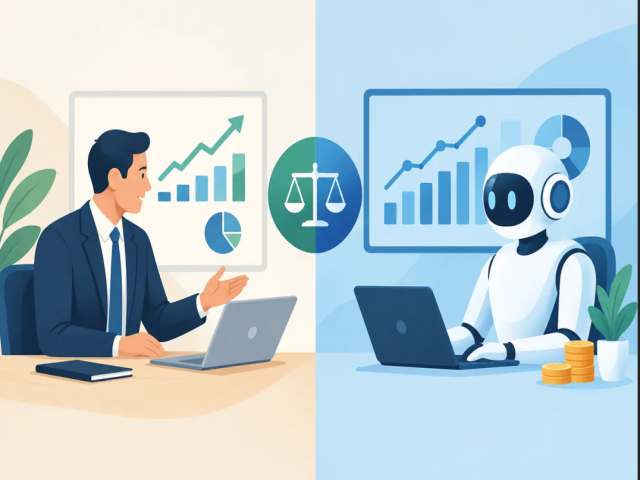
Actively managed versus robo advisors: compare personal strategy, automation, fees, risk, and control to choose a portfolio built around your goals.
A portfolio can look quiet on the surface while markets are moving fast underneath it. That is why the choice between actively managed versus robo advisors matters more than a preference for an app or an investment professional. You are deciding how your capital will respond to opportunity, uncertainty, and change while you focus on your work, family, or business.
For investors who want market exposure without spending every evening studying charts, both options can reduce the pressure of managing investments alone. The difference is in the decision-making process. Robo advisors run portfolios through automated rules. Active managers use research, market monitoring, and judgment to make decisions as conditions evolve. Neither is automatically right for every goal, but the better fit can make your investment plan feel far more intentional.
Actively Managed Versus Robo Advisors: The Core Difference
A robo advisor is designed to automate the fundamentals. You usually answer questions about your time horizon, financial goals, and comfort with risk. The platform then assigns you to a diversified portfolio, often built with low-cost funds, and may rebalance the allocation when it drifts from its target. It is a structured, hands-off approach built around consistency.
An actively managed portfolio takes a more responsive route. A manager or investment team evaluates market conditions, economic developments, company fundamentals, price trends, and risk signals. They may change exposure to equities, currencies, crypto assets, indices, or commodities when their strategy identifies a reason to act.
The practical distinction is simple: automated investing follows a framework established in advance, while active management can adjust the framework's implementation as new information arrives. That flexibility may be valuable in volatile markets, but it also depends on the quality of the people, process, controls, and reporting behind the strategy.
What a robo advisor does well
Robo advisors can be attractive because they make diversification and routine portfolio maintenance accessible. The onboarding process is typically fast, and the investor does not need deep trading knowledge to get started. For someone building long-term wealth through regular contributions, that convenience can be a meaningful advantage.
Automation can also remove emotion from routine decisions. Investors often feel tempted to sell during a downturn or chase assets after a sharp rally. A robo advisor is not influenced by fear, headlines, or excitement. It simply follows its programmed allocation and rebalancing rules.
That discipline has limits. A rule-based system does not independently decide that a particular market event deserves a different interpretation. It follows the model selected for your account. If your life, cash-flow needs, or risk tolerance changes, you need to update the plan rather than expect the algorithm to recognize the change on its own.
What active management is built to do
Active management is designed for investors who want professionals monitoring markets and making tactical decisions rather than merely maintaining a preset allocation. The goal is not to trade constantly for the sake of activity. The goal is to identify opportunities, manage downside exposure, and make adjustments when the investment case changes.
For example, an active strategy may increase caution when liquidity conditions tighten, reduce exposure to an overheated asset, or seek opportunity in a market that has been overlooked. It can also combine short-, mid-, and long-term views rather than treating every dollar as if it has the same purpose.
This approach can be especially relevant for investors seeking diversified exposure across global markets. Equities, fiat currencies, cryptocurrencies, indices, and commodities do not always move together. A team that follows those markets around the clock can assess where risk and opportunity may be shifting. That does not eliminate losses or guarantee profits, but it gives investors a decision process that can respond rather than simply remain static.
Fees, Performance, and the Questions That Matter
Cost is often the first comparison point, and it should be. Robo advisors generally charge a management fee based on assets in the account, in addition to the expenses inside the underlying funds. Their cost structure is usually straightforward because the service itself is largely automated.
Actively managed services may charge a higher ongoing fee, a performance-based fee, or a combination of both. A performance fee can align the manager's compensation with positive results, but investors should understand exactly how profits are calculated, when fees are charged, and whether losses are considered before additional performance fees apply.
Budrigantrade, for example, presents managed market access through investment programs and charges a commission on generated profit rather than positioning its service as a conventional fee-only advisory relationship. Before committing capital to any managed program, review the terms carefully, including withdrawal conditions, reporting practices, strategy risk, and the full fee schedule.
Low fees are useful, but they are not the only measure of value. A low-cost portfolio that does not match your goals, liquidity needs, or tolerance for market swings can still be the wrong choice. Likewise, a higher-cost active approach should earn its place through a clear strategy, transparent communication, and a management process you understand.
How Risk Changes in Each Approach
No investment format makes risk disappear. A robo advisor can diversify holdings, but it may still decline when broad markets fall. An actively managed portfolio can make defensive changes, yet those decisions can be wrong, early, or insufficient in a rapidly moving market.
The key question is not, “Which option is safe?” It is, “Which type of risk management fits the way I want my capital handled?” If you are comfortable accepting broad market movement in exchange for a simple, long-term automated plan, a robo advisor may suit you. If you want analysts and traders actively assessing market conditions, a managed strategy may be more aligned with your expectations.
Liquidity also deserves attention. Consider when you may need access to funds for an emergency reserve, a home purchase, business needs, or a major life change. Investments intended for near-term use should not be exposed to the same risk level as capital set aside for a longer horizon.
Choosing Based on Your Real Goal
A robo advisor can make sense if your priority is a low-maintenance portfolio, broad diversification, regular contributions, and a long-term buy-and-hold structure. It can be a practical starting point for investors who want organization without frequent strategic changes.
Active management may be a stronger fit if you value ongoing market oversight, want exposure beyond a standard stock-and-bond allocation, or prefer professionals to make trading decisions for you. It can also appeal to investors looking to organize capital around distinct time horizons, such as short-term income objectives, medium-term opportunities, and long-term wealth building.
Before choosing either path, be honest about what you expect. Do you want to check in once a year, or do you want visibility into a strategy that is being monitored and adjusted? Are you primarily focused on keeping fees minimal, or are you willing to pay for active expertise and a broader decision process? Do not choose a service because its recent returns look exciting. Choose it because its method, risk level, and access terms make sense for your financial life.
A Better Way to Think About Control
Some investors assume a robo advisor means giving up control and active management means gaining it. In reality, both require you to make the most important decision: setting the mandate. Control comes from knowing your objective, understanding what can happen to your capital, and selecting a provider whose process you can follow with confidence.
A well-built investment plan does not need daily attention from you. It does need a clear purpose. Whether you choose automated allocation or professionally managed market exposure, let your goals set the direction and let transparency, discipline, and realistic risk expectations guide every dollar you invest.
Recent Posts
-
-
Digital Wealth Management Trends to Watch
01 Nov 2026
-
Is Crypto Transaction Security Important?
01 Nov 2026
-
9 Best Financial Forecasting Tools for Investors
01 Nov 2026
-
-
Liquidity Planning for Investors That Works
26 Oct 2026
-
Can Entities Invest? A Practical Path to Growth
26 Oct 2026
-
-
High Yield Savings Versus Investing: Which Fits?
26 Oct 2026
-
Guide to Economic Indicators for Investors
22 Oct 2026
-
Retirement Portfolio Diversification Example
22 Oct 2026
-
When Portfolios Rebalance and Why It Matters
22 Oct 2026
-
How to Rebalance a Multi Asset Portfolio
22 Oct 2026
-
How to Protect Investment Accounts From Fraud
22 Oct 2026
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026