Small Business Treasury Allocation That Works
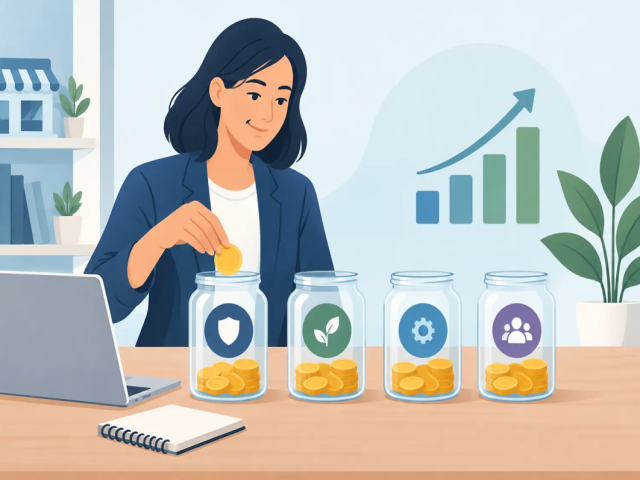
Build a small business treasury allocation that protects operating cash, creates income potential, and keeps capital ready for your next opportunity.
A strong small business treasury allocation begins with one practical question: how much of your company’s cash can stay committed without putting payroll, suppliers, taxes, or growth plans at risk? The answer is rarely “all of it” and rarely “none of it.” A business treasury should protect day-to-day operations first, then put truly surplus capital to work with a clear purpose, timeline, and level of risk.
For a growing company, idle cash can feel safe but costly. Inflation can quietly reduce its purchasing power, while opportunities for expansion, inventory, equipment, and market participation may pass by. Yet chasing returns with money needed next month can create a cash crisis faster than any market downturn. Smart allocation is about separating those jobs before making an investment decision.
What Small Business Treasury Allocation Means
Treasury allocation is the process of dividing business cash across operating reserves, near-term needs, and longer-term capital. It gives every dollar a role. Some cash must remain immediately available. Some can be reserved for planned spending. Some may be positioned for income or long-term growth.
This is not the same as putting the company’s account balance into one investment program. A treasury plan is a control system. It helps the owner see what money is essential to keep the business running and what money can be considered surplus capital.
The right mix depends on your revenue reliability, industry seasonality, debt obligations, payment cycles, and expansion plans. A consulting firm with monthly recurring revenue may hold a different reserve than a retailer preparing for a holiday inventory cycle. A construction business waiting 60 days for client payments needs more liquidity than a subscription-based software company with prepaid contracts.
Start With the Operating Cash Floor
Before considering yield, establish a minimum operating cash floor. This is the amount your business needs to meet commitments even if incoming revenue slows or a major customer pays late.
Add up recurring monthly costs such as payroll, rent, software, insurance, taxes, debt payments, supplier invoices, and essential marketing. Then consider the timing of those costs. A profitable business can still be short of cash if payments arrive after bills are due.
Many owners choose a reserve equal to three to six months of core operating expenses. Businesses with volatile sales, long receivables, seasonal demand, or concentrated clients may choose more. Companies with predictable recurring revenue and access to reliable credit may be comfortable with less. There is no universal percentage because liquidity needs are business-specific.
Keep this operating floor in cash or highly liquid, low-volatility holdings. Its job is reliability, not aggressive growth. If you would be forced to sell it at a bad time to cover payroll, it does not belong in a higher-risk allocation.
Include Taxes and Known Commitments
One common mistake is treating tax money as available capital. It is not. Sales tax, payroll tax, estimated income tax, and other liabilities should be separated as soon as possible. The same goes for a signed equipment purchase, annual insurance premium, planned inventory order, or upcoming loan payment.
A clean treasury view distinguishes between money you own freely and money your business is temporarily holding for a future obligation. That distinction can prevent a profitable quarter from becoming a stressful cash-flow problem.
Build Separate Time Horizons
Once the operating floor and known obligations are covered, divide remaining cash by when it may be needed. This makes risk decisions more rational because a one-year opportunity should not be funded with next week’s payroll money.
A useful approach is to organize capital into three buckets:
- Immediate liquidity: Operating reserves and funds needed within 30 days. Prioritize access and stability.
- Planned capital: Cash expected to be used in the next one to 12 months for inventory, hiring, equipment, taxes, or expansion. Favor lower-risk options with a timeline that matches the intended use.
- Strategic capital: Genuine surplus that is not required for near-term operations. This portion may be considered for diversified investment exposure and longer-term income goals.
The strategic bucket is where managed market participation may fit. It can give a business owner exposure to global equities, currencies, commodities, indices, or digital assets without personally monitoring markets throughout the day. But the timeline matters. Market-based investments can rise and fall, and returns are never guaranteed. A company should only allocate capital it can afford to leave invested through normal volatility.
Match Risk to the Business Goal
Every treasury position should have a purpose. If the goal is protecting a purchase fund for a delivery vehicle next quarter, capital preservation and access should lead the decision. If the goal is building wealth for a future second location three years away, the business may have more room for measured market exposure.
Risk tolerance is not just about how an owner feels when prices move. It is about what the business can withstand. Ask three direct questions: Could this capital decline in value? When might the business need it? What happens if it is not available at that time?
If the answer to the last question is missed payroll, delayed tax payments, or cancelled customer orders, the allocation is too aggressive. If the funds are surplus after reserves and upcoming investments are covered, a diversified strategy may be more appropriate.
Avoid concentrating treasury capital in a single asset, currency, customer-linked investment, or high-volatility market. Concentration can turn one unexpected event into a company-wide liquidity issue. Diversification does not remove risk, but it reduces dependence on one outcome.
Put a Written Policy Behind Your Allocation
A simple treasury policy turns good intentions into repeatable decisions. It does not need to be a lengthy corporate document. For many small businesses, one page can define the operating cash floor, target reserve range, permitted investment categories, approval process, and review schedule.
For example, a policy may state that the company will maintain four months of fixed operating expenses in liquid reserves; keep all tax funds separate; invest only capital not expected to be needed for 12 months; and review allocations quarterly. It may also set a maximum percentage for any one investment category.
This structure is especially valuable when revenue increases. Without rules, growing balances can tempt owners to make quick decisions based on headlines, social media momentum, or a single strong month. A policy creates discipline when markets feel exciting and when they feel uncertain.
Use Managed Exposure Carefully
For owners who do not have the time or trading expertise to manage positions themselves, a managed investment service can offer a practical way to pursue passive income from global markets. Budrigantrade is designed around this need, providing managed exposure and portfolio visibility for investors who want market participation without handling daily trading activity.
Still, convenience should never replace due diligence. Understand the investment timeline, withdrawal terms, fees or profit-sharing structure, assets involved, risk level, reporting process, and how quickly capital can be accessed. Review whether the strategy fits the business’s legal structure, tax situation, and cash-flow forecast. A qualified accountant or financial professional can help assess these questions for your specific business.
Transparency matters as much as performance. You should be able to see what portion of company cash is invested, what remains liquid, and whether the allocation continues to match the company’s needs. A treasury plan that cannot be clearly explained is difficult to manage.
Review the Allocation Before It Becomes Urgent
Treasury allocation should change as the business changes. Review it at least quarterly and after major events such as a large contract, new financing, acquisition, loss of a key customer, seasonal peak, or expansion decision.
Watch for signals that your liquidity target needs to increase: slower collections, rising payroll, higher inventory requirements, customer concentration, or unstable demand. On the other hand, recurring revenue growth and stronger working capital may create a larger strategic capital pool over time.
Do not evaluate the plan only by investment performance. A treasury allocation is working when the business can meet commitments confidently, respond to opportunities quickly, and pursue growth without putting essential operations at risk.
The most useful next step is simple: map your next 12 months of cash needs, set the amount your business cannot afford to lose or lock up, and give the remaining capital a deliberate job. That clarity can turn cash from a source of uncertainty into a stronger foundation for your next move.
Recent Posts
-
Best Practices for Investor Cybersecurity
09 Nov 2026
-
What Causes Investment Losses? 7 Key Reasons
09 Nov 2026
-
Investment Risk Comparison for Smarter Choices
09 Nov 2026
-
ETFs Versus Mutual Funds for Investment Goals
09 Nov 2026
-
-
Digital Wealth Management Trends to Watch
01 Nov 2026
-
Is Crypto Transaction Security Important?
01 Nov 2026
-
9 Best Financial Forecasting Tools for Investors
01 Nov 2026
-
Actively Managed Versus Robo Advisors Compared
01 Nov 2026
-
-
Liquidity Planning for Investors That Works
26 Oct 2026
-
Can Entities Invest? A Practical Path to Growth
26 Oct 2026
-
-
High Yield Savings Versus Investing: Which Fits?
26 Oct 2026
-
Guide to Economic Indicators for Investors
22 Oct 2026