How to Diversify Income Streams With Purpose
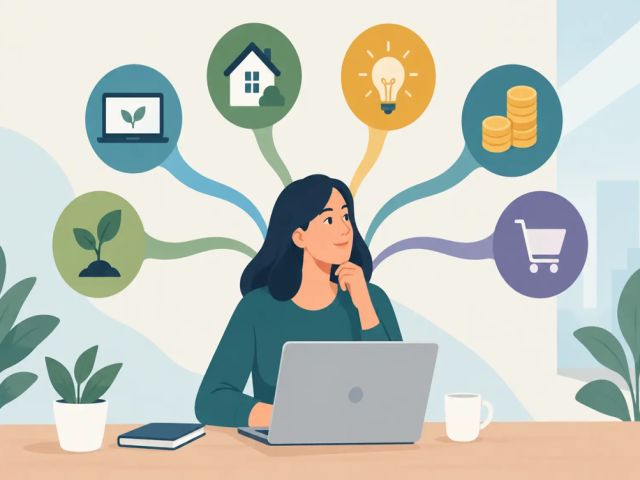
Learn how to diversify income streams with a practical mix of earned income, cash reserves, and managed market exposure built around your goals and risk.
A single paycheck can feel dependable until a contract ends, hours are reduced, a client leaves, or an unexpected expense arrives. Learning how to diversify income streams is not about chasing every money-making trend. It is about building more than one path to cash flow, so your financial progress does not rely on one employer, one customer, or one market outcome.
For working professionals, business owners, and first-time investors, the goal is simple: create a financial structure that can support today's needs while giving long-term wealth a chance to grow. That structure should be realistic, visible, and aligned with the level of risk you can comfortably carry.
What income diversification really means
Income diversification means earning money from sources that do not all respond to the same event in the same way. Your salary may provide stability. A service-based side business may provide flexible income. Interest-bearing cash products may support liquidity. Investments can offer a path to market-based growth and potential distributions over time.
The distinction matters because having several jobs is not automatically diversification. If all of your income depends on the same industry, the same few customers, or your constant availability, a single disruption can still affect everything. A stronger approach mixes active income - money earned through your time and work - with income sources that can continue operating with less day-to-day involvement.
Passive income also needs a clear definition. It rarely means zero effort or zero risk. Most passive income requires upfront capital, setup time, research, management, or a professional service provider. The advantage is that it can reduce the direct link between every hour you work and every dollar you earn.
Start with the income you already have
Before opening new accounts or committing money to an investment program, map your current position. List where your money comes from, how predictable each source is, and how much time it takes to maintain. This quickly shows whether you have true diversity or simply several versions of the same dependency.
Look at your monthly essentials first. Housing, food, insurance, debt payments, and household costs create your baseline. Then consider how much of that baseline is covered by reliable income and how much depends on variable work, commissions, or seasonal business activity.
A cash reserve should come before aggressive expansion. A reserve can prevent you from selling investments at the wrong time or taking on expensive debt when income slows. The right amount depends on job stability, family responsibilities, insurance coverage, and whether you own a business. For some people, a few months of essential expenses is a starting point. For others, especially freelancers and entrepreneurs, a larger reserve may be more appropriate.
Build income streams with different roles
The most effective strategy is not to collect random side hustles. Give each income stream a role in your plan. One may fund recurring expenses, another may build liquidity, and another may pursue longer-term growth.
Your primary income is often the foundation. Increasing skills, negotiating compensation, improving your business operations, or gaining higher-value clients can make this foundation stronger. Active income is not less valuable than passive income. It is often the capital source that makes investing possible.
A secondary active stream can provide flexibility. This might be consulting, freelance work, digital services, a specialized local business, or selling expertise in an area you already understand. The best option is usually connected to skills you have, rather than a complicated venture that demands a steep learning curve and large startup costs.
Then consider capital-based income. This category can include cash interest, dividends, bonds, real estate income, or managed market exposure. These options do not carry the same risks or timelines. Cash-oriented products may prioritize access and stability, while equity, commodity, currency, cryptocurrency, and index exposure can fluctuate significantly in value. Matching the investment type to its role is more useful than searching for the highest advertised return.
How to diversify income streams through investing
Investment exposure can expand your income opportunities beyond your paycheck or business, but it should be approached with discipline. Markets can create growth potential, yet returns are not guaranteed. Short-term price movement can be sharp, particularly in currencies, commodities, and digital assets.
A diversified investment approach spreads capital across assets, strategies, and time horizons. Rather than placing all available funds into one stock, one coin, or one market idea, an investor may allocate across multiple categories. This can reduce the impact of any single setback, though it cannot remove risk or prevent losses.
Time horizon is equally important. Funds needed for an upcoming move, tuition payment, or emergency should not be treated like capital set aside for a long-term wealth goal. Short-term needs generally call for greater liquidity and less exposure to volatile assets. Capital intended for a longer timeline may have more room to withstand market fluctuations.
For investors who do not want to trade independently, managed investing can offer a more hands-off route to market participation. A service such as Budrigantrade is designed to provide managed exposure across global markets while allowing clients to monitor their portfolio activity. The value of a managed model is not a promise of profit. It is the ability to delegate daily market monitoring and execution while remaining focused on your broader financial plan.
Before using any managed investment service, understand how it is compensated, what markets it accesses, how withdrawals work, what risks apply, and how account reporting is provided. Transparency is not a bonus feature. It is essential when another party is managing capital on your behalf.
Avoid concentration disguised as opportunity
Many people concentrate their income without realizing it. An employee may hold company stock, receive a company paycheck, and keep retirement savings heavily invested in the same sector. A small business owner may depend on one major client while investing most surplus cash into one speculative asset. Both situations can look profitable until the same event hits every source at once.
Diversification works best when the sources are genuinely different. A professional with a salary, a cash reserve, diversified market investments, and a consulting client base has more separation than someone with several gig apps that all rely on the same local demand.
Be especially careful with opportunities that promise fast, consistent, or risk-free returns. High potential return usually comes with higher uncertainty, less liquidity, or a greater chance of loss. If you cannot explain how an opportunity generates income, when your funds may be unavailable, and what could cause its value to fall, it deserves more research before it receives your capital.
Create a plan you can maintain
A sustainable income plan does not require ten accounts and constant monitoring. It requires regular decisions that are simple enough to repeat. Automating a portion of each paycheck toward savings or investing can build consistency without relying on perfect timing.
Use a clear order for new money. First, protect essential cash needs. Next, address high-cost debt where appropriate. Then direct a planned amount toward building or expanding income-producing assets. The percentage will vary by household. Someone with unstable income may prioritize reserves, while someone with secure employment and a longer horizon may dedicate more toward investments.
Review your mix every few months and after major life changes. A promotion, new business contract, home purchase, marriage, or change in debt can all affect how much risk makes sense. Review does not mean reacting to every market headline. It means checking whether your allocation still reflects your goals.
Track a few practical measures: the number of independent income sources you have, the percentage of essential expenses covered by reliable cash flow, the size of your emergency reserve, and the amount of your portfolio exposed to any one asset or sector. These numbers turn a broad ambition into a plan you can see.
Make diversification serve your financial well-being
The right mix is personal. A younger professional with few fixed obligations may accept more market volatility than a parent building near-term security. A business owner with irregular revenue may value liquid reserves more than an additional illiquid investment. There is no universal allocation that works for every investor.
What matters is moving from dependence to options. Each thoughtful income stream can give you more room to handle setbacks, pursue opportunities, and make decisions from a position of greater financial confidence. Start with one additional source that fits your skills, capital, and timeline, then build patiently from there.
Recent Posts
-
How to Read Portfolio Drawdowns With Confidence
06 Oct 2026
-
-
Are Investment Platforms Regulated in the US?
06 Oct 2026
-
Crypto Custody Service Review for Investors
06 Oct 2026
-
A Small Business Cash Reserve Example That Works
23 Sep 2026
-
Retirement Planning That Builds Real Flexibility
23 Sep 2026
-
Stocks Versus Bonds Allocation for Your Goals
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
Investment Platform Security Review Made Simple
19 Sep 2026
-
Best Portfolio Rebalancing for Lasting Growth
19 Sep 2026
-
Crypto Custody Versus Exchange Wallets Explained
19 Sep 2026
-
AI Investing: A Smarter Way to Build Wealth
14 Sep 2026
-
How to Set Investment Goals That Fit Your Life
14 Sep 2026
-
Retirement Income Guide for Lasting Cash Flow
14 Sep 2026