How to Set Investment Goals That Fit Your Life
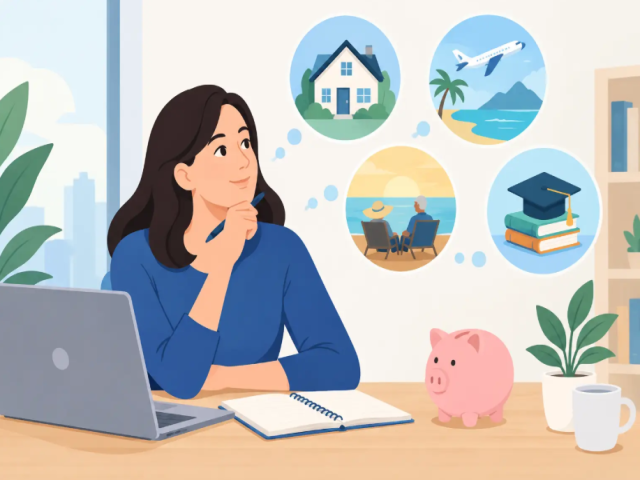
Learn how to set investment goals around your timeline, risk comfort, and income needs, then create a focused plan for long-term financial well-being.
A goal like “make more money” can feel motivating, but it cannot guide an investment decision. Knowing how to set investment goals means turning a hope for financial freedom into a clear destination, a realistic timeline, and a plan you can stay committed to when markets move in either direction.
For many investors, the appeal of managed market exposure is simple: your money can pursue growth while you focus on your work, family, or business. But passive investing should never mean passive thinking. The strongest results begin with a decision about what your capital needs to do for you, when you need it, and how much uncertainty you can reasonably accept.
Start With the Life Outcome, Not the Investment Product
Your investment goal should describe a real financial outcome before it describes a return percentage, market, or program. “I want to build a down payment within four years” is useful. “I want to invest in crypto” is not yet a goal. One identifies a destination. The other identifies a vehicle.
Think about the moments that would make a meaningful difference to your financial well-being. You may want to create an additional income stream, grow capital for retirement, fund a child’s education, expand a small business, or build reserves that give you more flexibility at work. Entity-based investors may be preparing for an equipment purchase, a new location, or a longer-term operating reserve.
A strong goal contains three elements: the amount you want to reach, the date or time range you are working toward, and the reason that money matters. That reason is more than a personal detail. It helps you avoid abandoning your plan because of short-term headlines or chasing a market trend that does not serve your larger objective.
How to Set Investment Goals With a Clear Time Horizon
Time is one of the most important filters in investing. It affects how much market movement you may be able to tolerate and how much liquidity you need from your capital. A practical way to organize your goals is to place them into short-, mid-, and long-term time horizons.
Short-term goals are often within one to three years. They might include a planned purchase, a cash-flow objective, or a business expense. Capital designated for a near-term need generally calls for more caution because you may not have enough time to recover from an unfavorable market period.
Mid-term goals commonly fall between three and seven years. This could be saving for a home, building a business fund, or creating a larger personal safety net. With more time available, investors may be able to consider a broader mix of opportunities, while still keeping the planned withdrawal date in view.
Long-term goals usually extend beyond seven years. Retirement planning, generational wealth, and future financial independence belong here. A longer timeline can give a portfolio more room to work through normal market cycles, but it does not remove risk. All investments can rise or fall in value, and no return should be treated as guaranteed.
The key is to avoid putting every dollar into one horizon. Money you may need next year should not be treated the same way as money intended for a decade from now. Separating these priorities can make your overall strategy more stable and reduce the pressure to withdraw long-term capital at the wrong time.
Put a Number Behind Each Goal
Vague goals are difficult to measure. Instead of saying you want “better passive income,” decide what that means in dollars. You may want to build a $25,000 reserve, generate a targeted amount of supplemental monthly income, or reach a portfolio value that supports a future lifestyle decision.
Once you have a target amount, work backward. Ask how much you can invest initially, how much you can contribute regularly, and how long your money can remain invested. Your starting deposit matters, but consistent contributions often have an equally powerful role. Even a modest automated contribution can build momentum because it removes the need to make a new decision every month.
Be realistic about the return assumptions you use. High projected returns can make any plan look easy on paper, but markets do not move in straight lines. A more disciplined plan accounts for periods of lower performance, changing economic conditions, and the possibility that you may need to adjust contributions. The goal is not to create the most exciting forecast. It is to create one you can actually follow.
Decide How Much Risk Fits Your Situation
Risk tolerance is personal. Two people with the same income can make very different investment decisions because their obligations, savings, experience, and comfort with market volatility are different.
Start by considering your financial foundation. If you have high-interest debt, unstable income, or no emergency cash reserve, directing all available money into market investments may create unnecessary pressure. Establishing basic financial breathing room can help you invest with more confidence and less emotional stress.
Then consider your reaction to fluctuations. Would a temporary decline make you withdraw immediately? Could you remain focused on a long-term plan if the value of your holdings moved sharply over a few weeks? There is no prize for choosing more risk than you can handle. A strategy only works if you can stay with it.
Diversification can help manage concentration risk by spreading exposure across different markets and asset types, such as equities, currencies, digital assets, indices, and commodities. It does not eliminate losses, and it does not guarantee profits. Still, it can prevent a single market event from determining the fate of your entire financial plan.
Match Your Investment Approach to Your Available Time
Some investors enjoy researching charts, economic news, and individual positions every day. Others want access to global markets without turning trading into a second job. Neither approach is automatically better. The right choice depends on your knowledge, schedule, and willingness to make active decisions under pressure.
A managed approach can be useful for investors who want professional market monitoring and execution while maintaining visibility over their account. Platforms such as Budrigantrade are built around this preference, giving clients access to managed strategies rather than requiring them to place and monitor trades on their own.
Before committing capital, understand how the service works. Review the available investment time frames, profit-sharing or commission structure, withdrawal process, account reporting, and the markets involved. If crypto funding is available, also consider the practical realities of digital asset transfers, including price volatility and transaction handling. Convenience is valuable, but clarity should always come first.
Build Flexibility Into the Plan
Investment goals should guide you, not trap you. A promotion, a new child, a business opportunity, an unexpected expense, or a change in retirement plans can all alter your priorities. Reviewing your goals every six to 12 months gives you a chance to adjust without reacting impulsively to daily market noise.
During a review, look at whether your target date has changed, whether your contributions still fit your budget, and whether your portfolio mix still reflects your comfort with risk. You may find that one goal needs more funding while another can take a longer path. That is progress, not failure.
It also helps to establish simple rules in advance. For example, decide how much of a bonus you will invest, what level of cash reserve you want to maintain, and when you will take profits or rebalance. Pre-set decisions can protect you from emotional choices when markets are moving quickly.
Keep Your Goal Visible and Your Expectations Grounded
The best investment goals are specific enough to measure and flexible enough to survive real life. Track deposits, account value, time remaining, and any withdrawals against the purpose you set at the beginning. Transparent account visibility can make it easier to see whether your actions are supporting the plan.
Do not judge a long-term goal by one week or one month of performance. Market participation involves uncertainty, and disciplined investors understand that temporary movement is part of the process. What matters is whether your strategy, risk level, and time horizon still fit the future you are trying to create.
A clear goal gives every dollar a job. Set yours with intention, fund it consistently, and let your investment decisions serve the life and financial freedom you want to build.
Recent Posts
-
AI Investing: A Smarter Way to Build Wealth
14 Sep 2026
-
Retirement Income Guide for Lasting Cash Flow
14 Sep 2026
-
-

Investment Taxes: Keep More of What You Earn
10 Sep 2026
-

How Are Crypto Gains Taxed for U.S. Investors?
10 Sep 2026
-

How to Secure Crypto Deposits Without Mistakes
10 Sep 2026
-

A Clear Guide to Investment Risk Tolerance
10 Sep 2026
-

-
-
Passive Income for Busy Professionals That Fits
07 Sep 2026
-
Managed Portfolios Versus Robo Advisors
07 Sep 2026
-
7 Best Inflation Hedges for Long-Term Investors
07 Sep 2026
-
A Practical Guide to Entity Based Investing
07 Sep 2026
-
-