Best Portfolio Rebalancing for Lasting Growth
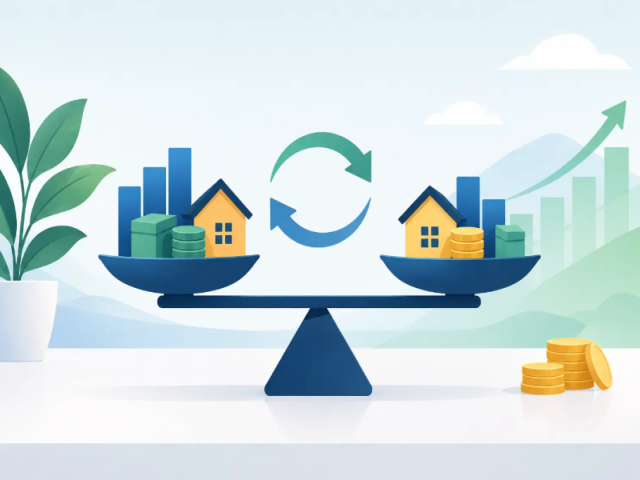
Find the best portfolio rebalancing approach for your goals, risk level, and timeline, with practical rules for managing change without chasing markets.
A portfolio can look healthy on the day you invest and become far more aggressive than you intended a year later. When one market rises faster than the rest, it can quietly take over your account. The best portfolio rebalancing process brings your money back in line with the goals, timeline, and risk level you chose in the first place.
That matters for investors who want passive income and long-term growth without spending every day watching price charts. Rebalancing is not about predicting the next winning asset. It is a disciplined way to manage exposure as global equities, currencies, crypto assets, commodities, and other holdings move at different speeds.
What Portfolio Rebalancing Actually Does
Every portfolio begins with an allocation, or a planned percentage for each type of investment. A growth-focused investor might hold more equities and higher-volatility assets. Someone saving for a near-term purchase may prefer a greater allocation to cash-like positions or lower-volatility instruments.
Those percentages do not stay fixed. Suppose you begin with 60% equities, 25% fixed-income or cash-oriented holdings, and 15% alternative assets. If equities have a strong run, they may eventually represent 75% of the portfolio. Your account may be worth more, but it now carries more stock-market risk than you originally accepted.
Rebalancing means trimming positions that have grown beyond their target and adding to areas that have fallen below target. In simple terms, it is a repeatable rule for avoiding a portfolio that drifts away from your financial plan.
This can feel counterintuitive. It may require reducing a holding that has performed well and allocating capital to an area that has lagged. Yet that is precisely the point: a rebalancing plan is designed to control risk, not chase the loudest market story.
The Best Portfolio Rebalancing Method Depends on Your Goal
There is no single allocation that works for every investor. The best portfolio rebalancing strategy depends on when you need the money, how much volatility you can realistically tolerate, and whether your goal is income, capital growth, or both.
For a long-term wealth goal, temporary market declines may be easier to accept because there is time to recover from volatility. A diversified growth allocation may make sense, provided the investor understands that values can move sharply in either direction.
For a short-term goal, such as a planned business expense, home purchase, or tuition payment, preserving access to capital often matters more than pursuing maximum growth. Rebalancing in this case may involve gradually reducing exposure to assets with large price swings as the deadline approaches.
Income-focused investors have another consideration. A portfolio built for regular distributions still needs risk controls. Reaching for unusually high yields can concentrate risk in one sector, one market, or one type of instrument. A balanced approach can help preserve flexibility when market conditions change.
Choose a Schedule That Prevents Emotional Decisions
Most individual investors do not need to rebalance every week or every day. Frequent changes can create unnecessary costs, tax consequences, and emotional pressure. More activity does not automatically mean better management.
A practical approach is to review your allocation on a set schedule, such as every six or twelve months. The benefit is consistency. You know when the review will happen, so you are less likely to make a major allocation decision because of a dramatic headline or a single volatile trading session.
Another approach uses percentage bands. For example, if your target allocation to equities is 60%, you might rebalance only when that portion moves outside a pre-set range, such as 55% to 65%. This allows normal market movement while creating a clear trigger for action when the portfolio has materially drifted.
For many investors, the strongest process combines both methods: conduct a regular review, but act sooner if an allocation moves significantly outside its range. The right range depends on the portfolio. A broadly diversified, lower-volatility allocation may use narrower bands, while a portfolio with crypto or commodity exposure may need wider bands to avoid reacting to routine price movement.
Use New Contributions Before Selling When Possible
Rebalancing does not always require selling assets. If one part of your portfolio is below target, new deposits can be directed toward that area. This is often a straightforward way to restore balance while keeping the process simple.
Imagine that your equity allocation has grown above its intended level while your cash-oriented or alternative allocation has fallen below target. Instead of immediately selling equities, future contributions can be allocated to the underweight category until the portfolio moves closer to plan.
This approach can be especially useful for investors making automatic deposits. Regular contributions create an opportunity to maintain discipline over time, even when markets are moving quickly. It can also reduce the urge to make large, sudden changes after a period of strong or weak performance.
Selling may still be necessary when drift is substantial, when withdrawals are planned, or when a position no longer fits the investor's objectives. Before making changes, consider transaction costs, liquidity, tax treatment, and the role each holding plays in the larger portfolio.
Diversification Is Not the Same as Owning More Assets
A long list of investments can create the appearance of diversification without delivering meaningful risk control. If multiple holdings react the same way to an economic shock, they may not provide much protection when it is needed.
Effective diversification considers how assets behave under different conditions. Equities can support growth potential, while cash-oriented holdings may provide stability and liquidity. Commodities, currencies, and selected alternative assets can add different sources of market exposure, but they also bring their own risks and can be volatile.
Crypto assets deserve special attention. They can offer access to an expanding digital market, but their price movements can be severe and unpredictable. If crypto is part of your strategy, establish a maximum allocation in advance and treat rebalancing as a guardrail. A sharp rally should not accidentally transform a small speculative position into the dominant risk in your account.
Avoid These Common Rebalancing Mistakes
The first mistake is rebalancing based on fear. Selling after a market decline simply because prices are falling can lock in losses and move you away from the strategy you selected. The second is the opposite: allowing a winning position to grow without limit because recent gains feel convincing.
Another mistake is confusing a target allocation with a promise of returns. Rebalancing can help manage risk and preserve discipline, but it cannot eliminate market losses or guarantee profit. Every asset class carries risk, and past performance does not determine future results.
Finally, do not let complexity become a barrier. If you do not have the time or confidence to evaluate multiple markets, a managed approach can provide structure. Budrigantrade is built for investors seeking professional market monitoring and transparent portfolio visibility without personally executing every trade. Even with managed services, investors should understand their program terms, timeline, withdrawal options, and risk exposure.
Build a Rebalancing Rule You Can Follow
A useful plan is specific enough to guide action during uncertainty. Start by defining your target mix based on your goal and time horizon. Next, choose a review schedule and a drift threshold. Then decide whether new deposits, withdrawals, or asset sales will be used to restore balance.
Write those rules down before markets become exciting or stressful. For example: review twice per year, rebalance only when an allocation differs from target by more than 5 percentage points, and use new contributions to address smaller gaps. Your personal rule may be different, but it should be clear enough that you can follow it when emotions are high.
The best rebalancing plan is not the most complicated one. It is the one that keeps your investment strategy connected to your real financial life. As your income, responsibilities, business needs, and future goals change, review the plan with the same care you bring to the portfolio itself.
Recent Posts
-
Investment Platform Security Review Made Simple
19 Sep 2026
-
Crypto Custody Versus Exchange Wallets Explained
19 Sep 2026
-
AI Investing: A Smarter Way to Build Wealth
14 Sep 2026
-
How to Set Investment Goals That Fit Your Life
14 Sep 2026
-
Retirement Income Guide for Lasting Cash Flow
14 Sep 2026
-
-

Investment Taxes: Keep More of What You Earn
10 Sep 2026
-

How Are Crypto Gains Taxed for U.S. Investors?
10 Sep 2026
-

How to Secure Crypto Deposits Without Mistakes
10 Sep 2026
-

A Clear Guide to Investment Risk Tolerance
10 Sep 2026
-

-
-
Passive Income for Busy Professionals That Fits
07 Sep 2026
-
Managed Portfolios Versus Robo Advisors
07 Sep 2026
-
7 Best Inflation Hedges for Long-Term Investors
07 Sep 2026