Retirement Planning That Builds Real Flexibility
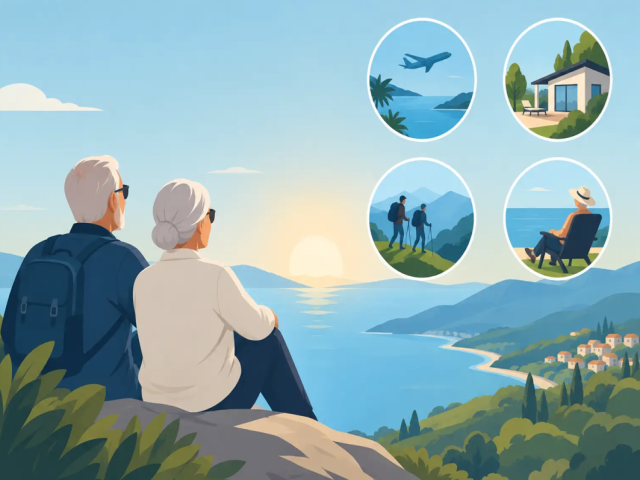
Retirement planning can turn regular contributions into a clearer path toward future income, flexibility, and financial confidence at every stage of life.
The number that matters most in retirement planning is not the balance you have today. It is the monthly income your future lifestyle will require, how long that income may need to last, and whether your investments are positioned to keep working while you do. A comfortable retirement is built through intentional decisions made long before you stop working.
For many people, retirement can feel too distant to prioritize. Yet delaying the process often means asking future contributions to do far more work. Starting with a clear strategy gives your capital more time to pursue growth, gives you more choices when markets change, and reduces the pressure to make rushed decisions later.
Retirement Planning Starts With Your Version of Freedom
Retirement does not look the same for everyone. One investor may want to leave a demanding career at 60 and travel regularly. Another may plan to continue working part-time, fund a business, support family members, or move to a lower-cost location. The goal is not simply to replace a salary. It is to create dependable financial capacity for the life you want.
Begin by estimating what your expenses could look like without full-time employment. Include housing, food, transportation, insurance, health care, taxes, debt payments, travel, and the activities that make retirement enjoyable. Then account for costs that are easy to overlook, such as home repairs, helping adult children, or long-term care needs.
A useful starting question is: if work income stopped tomorrow, what would need to arrive each month for life to feel secure? That figure gives your investment strategy a purpose beyond chasing a headline return.
Give Every Dollar a Job Across Time Horizons
A strong retirement strategy recognizes that not all money should take the same level of risk. Funds needed within a few years should generally be more accessible and less exposed to large market swings than capital intended for decades of growth. This is where separating short-, mid-, and long-term goals becomes valuable.
Your short-term reserves can help cover emergencies and near-term spending without forcing you to sell investments at an unfavorable time. Mid-term investments may support goals such as paying off a mortgage, funding a child's education, or preparing for an earlier retirement date. Long-term capital has more time to navigate market cycles and can be positioned for growth-oriented opportunities.
This approach does not eliminate risk. Equities, currencies, cryptocurrencies, indices, and commodities can all move sharply, sometimes without warning. But a diversified time-horizon strategy can prevent one market event from controlling your entire financial future.
Growth Matters, but Access Matters Too
Retirement assets should pursue growth, especially when inflation can steadily reduce purchasing power. At the same time, you need a plan for liquidity. An impressive portfolio value is less useful if you cannot access funds when a real need arises or if withdrawing them requires selling during a downturn.
The right balance depends on your age, income stability, retirement timeline, other sources of income, and comfort with market volatility. Someone with 25 years until retirement may accept more fluctuation than someone planning to retire in three years. Neither approach is automatically better. The key is matching investment exposure to the job that money needs to perform.
Build Contributions Into Your Normal Routine
Consistency can be more powerful than waiting for the perfect market moment. Regular contributions create a disciplined habit and allow you to invest through different market conditions. When prices are lower, the same contribution may buy more exposure. When prices are higher, you continue building your long-term position rather than standing on the sidelines.
Automation removes much of the friction. Setting a recurring contribution shortly after payday can make retirement funding part of your financial operating system, not a decision you must revisit every month. Even a modest amount can become meaningful when contributions are sustained and investment growth has time to compound.
Before increasing investment contributions, make sure high-interest debt and basic emergency reserves are being addressed. Retirement planning works best when it sits on a stable foundation. Investing money you may urgently need next month can create unnecessary pressure and lead to withdrawals at the wrong time.
Use Diversification as a Form of Protection
Putting all retirement capital into one company, one industry, one currency, or one asset class may produce exciting results in a strong period. It can also create serious vulnerability when conditions reverse. Diversification is not about avoiding every loss. It is about reducing the chance that one poor outcome damages your entire plan.
Global market exposure can offer access to different sources of potential return. Equities may support long-term growth, while commodities can respond differently to inflation and supply conditions. Currency markets and digital assets may provide additional opportunities, but they also carry distinct risks and can be highly volatile.
Managed market exposure can appeal to investors who want broader participation without personally monitoring charts, economic reports, or trading sessions every day. A platform such as Budrigantrade is designed around this need, offering managed access across global markets with portfolio visibility for investors who prefer a more hands-off approach. Still, managed investing is not risk-free, and no analyst, system, or strategy can guarantee profits.
Transparency should remain central to any decision. Understand where your money is invested, how performance is reported, when withdrawals are available, what fees apply, and what conditions may affect returns. If an opportunity cannot clearly explain those points, it does not belong at the center of your retirement strategy.
Plan for Inflation, Taxes, and Longer Lives
Many retirement plans fail not because the investor ignored saving, but because they underestimated how long the money needed to last. A retirement that begins at 65 can easily span 25 or 30 years. Inflation during that period can make everyday expenses significantly more expensive.
This is why holding every dollar in cash can be a quiet risk. Cash offers stability and immediate access, but its purchasing power may decline over time. Growth assets can help address inflation, although they come with price fluctuations. Your plan needs both: capital available for near-term needs and investments with the potential to support future purchasing power.
Taxes also deserve attention. Withdrawals from different account types can be treated differently, and investment gains may have tax consequences. For US investors, coordinating taxable accounts, workplace retirement plans, IRAs, and other holdings can improve how much of your portfolio ultimately supports your lifestyle. A qualified tax professional or financial adviser can help clarify choices based on your individual circumstances.
Review Your Plan Without Reacting to Every Headline
A retirement plan should not be set once and forgotten, but it should not be rebuilt every time markets become noisy. Review your goals, contribution level, asset mix, and projected income at least annually, as well as after major life events such as marriage, divorce, a career change, inheritance, or a change in health.
During a review, ask whether your retirement date has changed, whether expenses have increased, and whether your portfolio has become more concentrated than intended. If a strong market run has pushed one asset category far above its target share, rebalancing may help restore the level of risk you originally chose.
Avoid making emotional moves based on a single week of market news. Selling after a decline can turn a temporary loss into a permanent one, while aggressively buying into a surge can leave you overexposed. Calm, scheduled decisions are usually more useful than reactive ones.
Turn Retirement Planning Into a Living Strategy
The best retirement plan is not a fixed document or a distant promise. It is a living strategy that evolves with your income, responsibilities, opportunities, and definition of freedom. Start with the income you want your future life to support, automate what you can, diversify thoughtfully, and stay clear-eyed about risk.
Your future self does not need a perfect prediction of the market. It needs a plan that keeps moving forward, one purposeful contribution and one informed decision at a time.
Recent Posts
-
A Small Business Cash Reserve Example That Works
23 Sep 2026
-
Stocks Versus Bonds Allocation for Your Goals
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
Investment Platform Security Review Made Simple
19 Sep 2026
-
Best Portfolio Rebalancing for Lasting Growth
19 Sep 2026
-
Crypto Custody Versus Exchange Wallets Explained
19 Sep 2026
-
AI Investing: A Smarter Way to Build Wealth
14 Sep 2026
-
How to Set Investment Goals That Fit Your Life
14 Sep 2026
-
Retirement Income Guide for Lasting Cash Flow
14 Sep 2026
-
-

Investment Taxes: Keep More of What You Earn
10 Sep 2026
-

How Are Crypto Gains Taxed for U.S. Investors?
10 Sep 2026
-

How to Secure Crypto Deposits Without Mistakes
10 Sep 2026
-

A Clear Guide to Investment Risk Tolerance
10 Sep 2026