When Should Portfolios Rebalance for Growth?
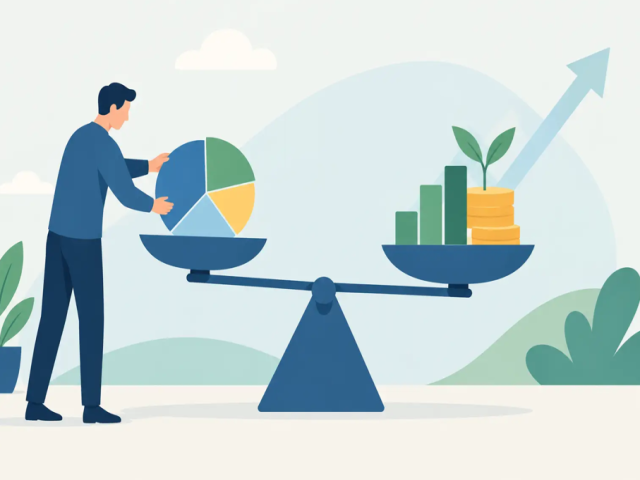
Learn when should portfolios rebalance, which triggers matter, and how a disciplined plan can manage risk while keeping long-term goals in view over cycles.
A portfolio can look healthy on the surface while quietly moving away from the plan you built. A strong run in technology stocks, a sudden crypto rally, or a drop in one currency can leave one part of your investments carrying far more weight than intended. That is why the question of when should portfolios rebalance matters. Rebalancing is not about reacting to every market headline. It is about restoring discipline when market movement changes your risk exposure.
For investors pursuing long-term wealth, passive income, or a more balanced path across global markets, a clear rebalancing approach can turn volatility from a source of stress into a moment for thoughtful portfolio management.
What portfolio rebalancing actually does
Rebalancing means adjusting investments back toward their intended allocation. If you began with 60% equities, 20% fixed-income exposure, 10% commodities, and 10% cash or alternatives, market performance will eventually change those percentages. If equities rise sharply, they may become 70% or 75% of your portfolio without you adding another dollar.
That shift can increase the potential for gains, but it also increases the amount of risk tied to a single market direction. Rebalancing brings the portfolio closer to its original design by reducing overweight positions and adding to underweight ones.
The principle is simple: a portfolio should reflect your goals, time horizon, and comfort with risk, not merely the investments that performed best recently. It can also encourage a valuable habit: taking some gains from assets that have risen and redeploying capital into areas that have become relatively less expensive.
When should portfolios rebalance?
There is no universal date that fits every investor. The best schedule depends on your investment strategy, account type, transaction costs, tax situation, and how quickly the underlying markets move. Still, most disciplined approaches use one of three triggers: time, allocation bands, or major life changes.
Rebalance on a regular schedule
A calendar-based review is the easiest method for investors who want structure without watching markets every day. Quarterly, semiannual, or annual reviews are common. An annual rebalance may be enough for a long-term investor with a diversified, relatively stable portfolio. Quarterly reviews can make more sense when an account includes higher-volatility assets such as cryptocurrencies, growth equities, commodities, or foreign currencies.
A scheduled review does not mean every holding must be traded on that date. It simply creates a checkpoint. If your allocation remains close to target, doing nothing may be the right decision. The objective is consistency, not constant activity.
Rebalance when an allocation moves beyond a set range
Threshold-based rebalancing is more responsive. Before investing, set a permitted range around each target allocation. For example, a 40% equity allocation may have a range of plus or minus 5 percentage points. If it rises above 45% or falls below 35%, the portfolio is reviewed and potentially adjusted.
This approach is useful because it focuses on meaningful changes in risk rather than the calendar. It may also reduce unnecessary transactions during calm periods. The trade-off is that it requires monitoring, either through a platform, a managed service, or a personal tracking process.
For a portfolio with several fast-moving asset classes, a percentage-based band can be more practical than an annual check alone. A 10% crypto allocation that becomes 22% after a strong rally changes the character of the entire portfolio. That may call for attention even if the next scheduled review is months away.
Rebalance after a major change in your financial life
Markets are not the only reason allocations need to change. A new job, business expansion, home purchase, retirement plan, inheritance, or change in family responsibilities can reshape your financial priorities. Your old target mix may no longer fit.
If you are saving for a near-term purchase, preserving capital may become more important than pursuing maximum growth. If your income rises and your long-term goals become more ambitious, you may decide that a larger growth allocation is appropriate. In these cases, rebalancing is not just restoring an old plan. It is updating the plan to serve where you are now.
Avoid rebalancing because of fear or excitement
The most common mistake is confusing rebalancing with market timing. Selling everything after a sharp decline or moving heavily into a rally because it feels unstoppable is an emotional decision, not a portfolio process.
A disciplined rebalance can require actions that feel uncomfortable. It may mean trimming an asset that has delivered exciting returns. It may mean adding to an area that has been disappointing. That is precisely why the rules should be decided before emotion takes over.
This does not mean ignoring new information. A major change in an asset's fundamentals, liquidity, regulation, or long-term outlook can justify a review. But that review should consider the full portfolio and your objectives, not one dramatic daily price movement.
How often is too often?
Rebalancing too frequently can create friction. Every adjustment may involve spreads, trading costs, taxes in taxable accounts, and the possibility of selling a winning position before its trend has fully developed. Excessive trading can also turn a long-term investment plan into a series of short-term guesses.
On the other hand, waiting too long can allow risk concentration to build unnoticed. An investor who intended broad diversification may discover that one asset class now drives most of the portfolio's daily movement.
For many investors, reviewing allocations quarterly and taking action only when a holding crosses a predefined band is a balanced starting point. A conservative investor with mostly lower-volatility assets may prefer a semiannual or annual process. An investor with meaningful exposure to crypto, currencies, or actively traded global markets may need closer oversight.
The right frequency is the one that keeps your portfolio aligned without creating unnecessary activity.
Rebalancing across different asset types
Not all investments should be treated the same way. Equities can experience extended growth periods, while commodities and currencies may move in shorter, more cyclical patterns. Crypto assets can change rapidly enough that a modest initial allocation becomes a major portfolio position in a short period.
This is why a diversified global approach needs clear limits for each asset category. Rather than treating every investment as a separate bet, view them as parts of one financial plan. Equities may support long-term capital growth, selected fixed-income or cash positions may support stability, and alternatives may offer diversification or a different source of opportunity. The intended role of each allocation should guide rebalancing decisions.
For investors using managed strategies, professional monitoring can be especially useful when markets operate across time zones and asset classes move at different speeds. Budrigantrade's managed approach is designed around ongoing market observation and portfolio visibility, helping clients stay connected to their investment strategy without personally managing every market decision.
Use cash flows before selling when possible
Rebalancing does not always require selling an investment. New deposits, dividends, interest, or withdrawals can help bring a portfolio back toward target weights.
If equities have grown beyond their intended allocation, a new contribution can be directed toward underweight areas instead of immediately selling shares. This can reduce transaction activity and may limit taxable events in a taxable account. Likewise, when withdrawing funds, taking them from an overweight category may improve alignment.
This method works best for investors who contribute regularly. It may not fully correct a large allocation drift, but it can make ongoing maintenance more efficient.
A practical rebalancing framework
Start by defining a target allocation that matches your timeline and risk tolerance. Then choose a review schedule and set clear drift bands for each major category. Keep the rules simple enough to follow under pressure.
At every review, ask three questions: Has my portfolio moved far enough from target to change my risk level? Have my personal goals or cash needs changed? Can new deposits or planned withdrawals do part of the rebalancing work?
Also consider account-level details. Taxable accounts, retirement accounts, entity accounts, and crypto holdings may each have different tax, custody, liquidity, or transaction considerations. Investors should understand those implications or seek qualified tax and financial guidance before making substantial changes.
Let the plan lead
Rebalancing is not a promise of profit, and it cannot prevent losses when markets decline. What it can do is keep a portfolio from being shaped entirely by recent winners, sudden fear, or market noise. It reinforces the allocation you chose for a reason.
Set the rules while you are calm, review them consistently, and let each adjustment serve a clear financial purpose. A portfolio that stays aligned with your real goals can give you a more confident foundation for pursuing long-term growth and financial well-being.
Recent Posts
-
Platform Security Review for Confident Investors
08 Oct 2026
-
How to Invest Business Cash Reserves Wisely
08 Oct 2026
-
How to Calculate Compound Returns on Investments
08 Oct 2026
-
Alternative Assets Trends Reshaping Portfolios
08 Oct 2026
-
How to Read Portfolio Drawdowns With Confidence
06 Oct 2026
-
-
Are Investment Platforms Regulated in the US?
06 Oct 2026
-
How to Diversify Income Streams With Purpose
06 Oct 2026
-
Crypto Custody Service Review for Investors
06 Oct 2026
-
A Small Business Cash Reserve Example That Works
23 Sep 2026
-
Retirement Planning That Builds Real Flexibility
23 Sep 2026
-
Stocks Versus Bonds Allocation for Your Goals
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
15 Best Investor Due Diligence Questions
23 Sep 2026
-
Investment Platform Security Review Made Simple
19 Sep 2026