Retirement Portfolio Diversification Example
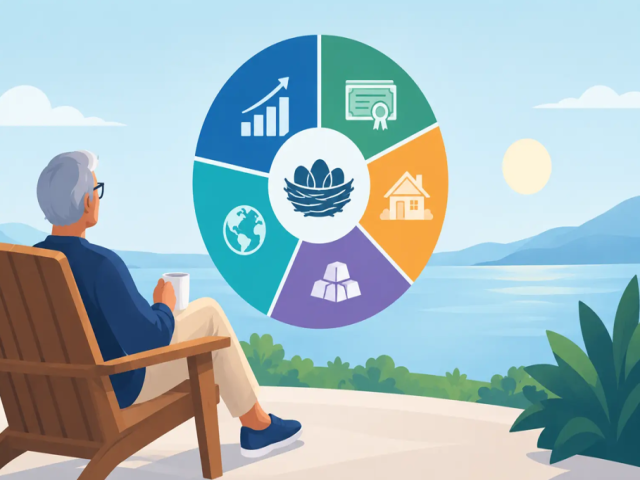
See a retirement portfolio diversification example built for growth, income, and stability, with practical adjustments for your timeline and goals today.
A retirement portfolio diversification example is most useful when it answers a real question: if one part of the market falls sharply, what else in your retirement account can keep working for you? For investors building long-term financial well-being, diversification is not about owning as many investments as possible. It is about assigning each part of your capital a purpose - growth, income, stability, or liquidity - so your future is not tied to a single company, country, currency, or market trend.
Retirement investing is a long game, but it is not a set-it-and-forget-it guessing game. Your mix should reflect when you expect to need the money, how much volatility you can realistically tolerate, and whether you need current income or primarily want future growth. A thoughtfully diversified portfolio gives you a clearer framework for pursuing passive income and long-term wealth without needing to react to every market headline.
A Retirement Portfolio Diversification Example for a 20-Year Horizon
Consider an investor age 45 who expects to retire around age 65. They have stable employment income, contribute regularly to retirement savings, and do not plan to withdraw from the portfolio for at least two decades. Because the time horizon is long, this investor can generally place more emphasis on growth assets while still maintaining stabilizers for difficult market periods.
Here is one illustrative allocation for a portfolio of $100,000:
- 45% U.S. equities: $45,000
- 20% international developed-market equities: $20,000
- 10% emerging-market equities: $10,000
- 15% high-quality bonds: $15,000
- 5% real assets or commodities exposure: $5,000
- 5% cash or short-term instruments: $5,000
This is an educational example, not a personalized investment recommendation. The right percentages can change significantly based on tax treatment, debt, emergency savings, pension income, health needs, and personal risk tolerance.
The growth engine: 75% in global equities
In this example, 75% is allocated to stocks. That is a meaningful commitment to growth, but it is not a bet on one market. U.S. equities may provide exposure to established companies across technology, health care, financial services, industrials, and consumer sectors. International developed-market stocks add companies based in regions such as Europe, Japan, Canada, and Australia. Emerging-market equities can offer access to faster-growing economies, though they usually bring greater political, currency, and price volatility.
The purpose of this global mix is straightforward. Even the strongest domestic market can experience years of weak performance. Holding international assets means your retirement plan is not entirely dependent on the U.S. economy, a single interest-rate environment, or one currency. International markets can also lag for extended periods, which is why diversification requires patience rather than constant switching into last year's winner.
The stabilizers: bonds and cash
The 15% bond allocation is designed to provide a potential counterbalance when stock prices become unsettled. High-quality government and investment-grade corporate bonds may generate interest income and tend to be less volatile than equities, although bond values can decline when interest rates rise. They are not risk-free, but they can make a retirement portfolio easier to hold through a downturn.
The 5% cash or short-term allocation has a different job. It is not there to chase high returns. It creates flexibility. Cash can cover planned near-term needs, allow an investor to rebalance into assets that have fallen, and reduce the pressure to sell long-term investments at an unfavorable time. For someone with no separate emergency fund, the appropriate cash reserve may need to be higher.
The diversifier: real assets and commodities
The remaining 5% goes to real assets or broad commodities exposure. This category may include assets connected to energy, metals, agriculture, infrastructure, or real estate. It can behave differently from traditional stocks and bonds, particularly during inflationary periods or supply shocks.
That difference is valuable, but modest sizing matters. Commodity prices can be volatile and do not always provide steady income. Real estate can face interest-rate pressure and changing occupancy conditions. A small allocation can broaden the portfolio without allowing one specialized sector to dominate the outcome.
Why This Mix Works Better Than a Single-Market Bet
The goal is not to make every holding rise at the same time. In fact, a diversified portfolio often feels disappointing in the moment because one segment may be falling while another is holding up or moving higher. That is the point. If every investment responds identically to the same event, the portfolio has less real diversification than it appears to have.
Imagine a period where U.S. growth stocks decline after interest rates rise. Bonds may still be pressured, but short-term instruments can retain value, certain commodity exposures may benefit from inflation, and international markets may follow a different economic path. No allocation guarantees protection. The advantage is that one negative market event has fewer opportunities to damage every dollar you have invested.
Diversification also helps limit emotional decisions. Investors who hold only a few highly correlated assets can feel forced to sell after a sharp decline. A portfolio designed around several sources of return gives you more room to stay focused on the retirement objective rather than the price movement of the week.
Adjusting the Example as Retirement Gets Closer
A 45-year-old and a 63-year-old may both want financial independence, but they face different risks. The investor with 20 years until retirement has time to potentially recover from major stock-market declines. The investor planning withdrawals within a few years has less time and may be more exposed to sequence-of-returns risk - the danger of selling investments after losses while simultaneously drawing income.
For example, an investor nearing retirement might gradually shift toward a mix such as 50% global equities, 35% bonds, 10% cash and short-term instruments, and 5% real assets. The lower stock percentage can reduce volatility, while the larger allocation to bonds and cash may support near-term withdrawals.
This does not mean every retiree should become highly conservative. Someone retiring with strong pension income, low expenses, and a long expected retirement may still need meaningful growth exposure to address inflation and longevity. On the other hand, a person relying entirely on portfolio withdrawals may value a larger reserve of stable assets. Your timeline matters, but so do your income sources and spending needs.
Rebalancing Keeps the Strategy Intentional
Markets move, and your allocation will move with them. If equities have a strong year, a 75% stock allocation could quietly become 82% or more. That may increase risk beyond what you originally chose. Rebalancing means periodically returning the portfolio toward its target weights by adding new contributions to underweight areas or trimming positions that have grown too large.
For many long-term investors, reviewing allocations once or twice a year is enough. Rebalancing every time markets move can create unnecessary trading, taxes in taxable accounts, and stress. The objective is disciplined maintenance, not constant activity.
A managed approach can be useful for investors who want exposure to global markets but do not have the time or confidence to monitor positions, assess changing conditions, and execute adjustments themselves. Budrigantrade is built around accessible portfolio visibility and active market monitoring, helping investors pursue broader market participation without personally managing every trade. Still, investors should understand how any managed program is structured, what risks it takes, how returns are generated, and what fees apply.
Diversification Is Not a Promise of Profit
A balanced allocation can reduce concentration risk, but it cannot eliminate losses. Stocks can decline globally, bonds can lose value, currencies can fluctuate, and commodity markets can change quickly. A diversified retirement portfolio may underperform a narrowly focused portfolio during a boom in one asset class. That trade-off is often acceptable because retirement planning is about staying financially capable across many possible market environments, not winning one short-term race.
Before committing money, make sure high-interest debt is addressed, emergency savings are available, and the retirement account fits your tax situation. Be especially cautious with investments that promise fixed or unusually high returns with little explanation of the underlying risk. Transparency, appropriate time horizons, and a clear withdrawal plan matter as much as the allocation itself.
The best retirement portfolio is not the one with the most holdings or the boldest forecast. It is the one you understand, can fund consistently, and can remain committed to when markets become uncomfortable. Start with a mix that matches your life, review it with purpose, and let disciplined diversification give your long-term goals room to grow.
Recent Posts
-
Guide to Economic Indicators for Investors
22 Oct 2026
-
When Portfolios Rebalance and Why It Matters
22 Oct 2026
-
How to Rebalance a Multi Asset Portfolio
22 Oct 2026
-
How to Protect Investment Accounts From Fraud
22 Oct 2026
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026
-
How to Set Financial Goals That Build Wealth
20 Oct 2026
-
Robo Advisors Versus Brokers for Your Goals
20 Oct 2026
-
-
-
When Should Portfolios Rebalance for Growth?
08 Oct 2026
-
Platform Security Review for Confident Investors
08 Oct 2026
-
How to Invest Business Cash Reserves Wisely
08 Oct 2026
-
How to Calculate Compound Returns on Investments
08 Oct 2026
-
Alternative Assets Trends Reshaping Portfolios
08 Oct 2026
-
How to Read Portfolio Drawdowns With Confidence
06 Oct 2026