When Portfolios Rebalance and Why It Matters
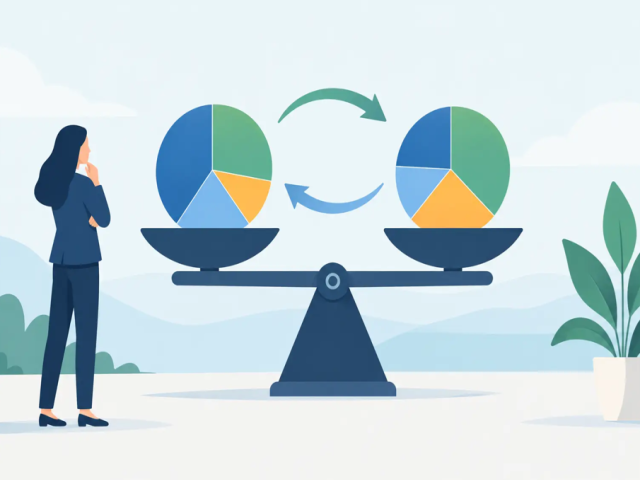
Learn when portfolios rebalance, what triggers changes, and how disciplined adjustments can keep your investment strategy aligned with your goals over time.
A portfolio can drift away from your original plan long before you notice it. When portfolios rebalance, they are brought back toward the mix of assets you chose for your goals, time horizon, and comfort with market risk. It is a disciplined adjustment, not a prediction that one market is about to rise or fall.
For investors seeking managed exposure and passive income opportunities, rebalancing is one of the quiet processes that can help keep a strategy organized while markets move around the clock. Stocks, currencies, crypto assets, commodities, and indices do not move at the same pace. What starts as a balanced allocation can become heavily weighted toward whichever asset has recently performed best - or suffered the smallest decline.
What Rebalancing Actually Does
Rebalancing means buying, selling, or redirecting new funds so a portfolio returns to its intended asset allocation. Imagine an investor begins with 60% equities, 20% fixed-income or cash-like holdings, 10% commodities, and 10% digital assets. After a strong stock market run, equities may grow to 72% of the portfolio while other positions make up less than planned.
At that point, the portfolio may carry more equity-market risk than the investor agreed to take. Rebalancing could mean reducing part of the overweight equity position and adding to underweight assets. The goal is not to eliminate risk. It is to keep risk connected to the investor's original strategy.
This matters because performance can create an illusion of safety. A fast-rising asset feels attractive precisely when it has become a larger part of the portfolio. Yet concentration can increase the impact of a reversal. Rebalancing introduces a rule-based response when emotion might otherwise take control.
When Portfolios Rebalance: Three Common Triggers
There is no single schedule that fits every investor. The right timing depends on the assets held, transaction costs, tax considerations, account type, and the purpose of the capital. Most portfolio strategies use one of three approaches, or a combination of them.
Calendar-Based Rebalancing
A calendar-based approach checks allocations at regular intervals, such as monthly, quarterly, semiannually, or annually. Quarterly reviews are common because they create a consistent rhythm without reacting to every daily headline.
This approach is straightforward and easy to understand. It is especially useful for investors who want oversight without monitoring markets themselves. The trade-off is that a portfolio can drift significantly between review dates if one asset class moves sharply.
More frequent reviews are not automatically better. Frequent trading can create costs and may cause unnecessary changes when market movements are temporary. A disciplined schedule should support the investment plan, not turn a long-term strategy into constant activity.
Threshold-Based Rebalancing
Threshold-based rebalancing happens when an asset allocation moves beyond a predetermined range. For example, an investor with a 50% equity target might rebalance if equities rise above 55% or fall below 45%.
This method responds to meaningful changes rather than the calendar. It can be effective in volatile markets, where a fixed annual review may be too slow. However, it requires clear rules. Without them, investors can be tempted to treat every small move as a reason to trade.
Thresholds should reflect the portfolio's purpose. A long-term growth account may accept wider ranges because short-term volatility is expected. A portfolio intended to support near-term cash flow may require tighter risk controls and more stable allocations.
Cash-Flow Rebalancing
Rebalancing does not always require selling a successful investment. New deposits, dividends, interest payments, or withdrawals can be directed toward the parts of the portfolio that are below target.
For example, if commodities have fallen below their intended allocation, a new contribution could be allocated there instead of adding more to an already overweight equity position. This can limit trading activity and may reduce taxable sales in certain account structures. It also makes each deposit part of a deliberate strategy rather than a disconnected transaction.
Why Rebalancing Is More Than a Routine Adjustment
A portfolio is not just a collection of positions. It is a financial plan expressed through assets with different roles. Equities may be positioned for growth. Currency exposure may add global diversification. Commodities can react differently to inflation or supply shocks. Digital assets may offer growth potential but often bring higher volatility.
Rebalancing keeps those roles from being overwhelmed by recent market performance. It can help prevent a portfolio designed for diversification from becoming a one-market bet.
It also creates a practical form of discipline: trimming portions of assets after substantial gains and adding to areas that have fallen below their target weight. That does not guarantee a profit, and an underperforming asset can continue to decline. But the approach avoids allowing enthusiasm or fear to make every allocation decision.
For a managed strategy, this process may be informed by broader market conditions, liquidity needs, risk limits, fundamental research, and technical signals. Portfolio managers may decide that a target allocation itself needs to change because the investor's objective has changed or because the strategy has been formally updated. That is different from ordinary rebalancing. One adjusts holdings back to the plan; the other changes the plan itself.
Rebalancing Across Different Investment Timelines
The timeline behind your investment matters as much as the assets you own. A short-term objective, such as building funds for a business purchase or planned expense, generally needs a different balance than a long-term wealth-building objective.
Short-term portfolios often prioritize capital availability and lower volatility. In that case, rebalancing may focus on preventing growth-oriented assets from becoming too large a share of funds needed soon. A major market decline at the wrong moment can have greater consequences when there is little time to recover.
Mid-term portfolios can often accommodate a measured level of growth exposure while maintaining enough stability for planned goals. Rebalancing helps ensure that a period of strong returns does not accidentally raise risk beyond what the timeline can support.
Long-term portfolios usually have more room to tolerate market cycles, but they still need boundaries. A 10-year horizon does not mean every asset allocation is appropriate. It means the investor can make allocation decisions with more patience and less dependence on short-term price movements.
The Costs and Trade-Offs to Consider
Rebalancing is useful, but it is not free from trade-offs. Selling positions can create taxes in taxable accounts, depending on gains and local rules. Transactions may carry spreads, commissions, or other costs. In less liquid markets, executing a large adjustment may also affect the price received.
There is an opportunity cost as well. An asset that has risen sharply may continue rising after it is trimmed. Rebalancing accepts that possibility because the purpose is risk control, not capturing every final dollar of a trend.
That is why good rebalancing decisions are based on predefined allocation ranges, market conditions, and investor objectives rather than fear of missing out. The most effective process is often the one an investor can follow through both rallies and drawdowns.
What Managed Investors Should Watch For
If you use a managed investment service, you do not need to execute every adjustment personally. You should still understand the framework guiding your capital. Transparent portfolio visibility, clear reporting, and a defined strategy make it easier to see whether holdings remain aligned with your expectations.
Ask how often allocations are reviewed, whether adjustments are calendar-based or threshold-based, and how the strategy handles unusually volatile conditions. It is also reasonable to ask how cash withdrawals, new deposits, and profit distributions affect the allocation.
Platforms such as Budrigantrade position managed market exposure as an accessible option for investors who want professional monitoring without personally trading each day. Even with a managed approach, investors should review their goals periodically, understand the risks of each market exposure, and avoid treating past performance as a promise of future results.
A Better Way to Think About Portfolio Changes
Rebalancing should not feel like punishment for a winning investment or a reward for a losing one. It is a way of honoring the decision you made before market noise became loud. The strongest allocation is rarely the one that looked smartest last month. It is the one that remains suitable for your financial goals, available time, and ability to withstand uncertainty.
Set an allocation you can realistically stay with, define when it should be reviewed, and revisit the plan whenever your life or financial priorities change. That gives every market movement a place in your strategy without allowing it to take control of the strategy.
Recent Posts
-
Guide to Economic Indicators for Investors
22 Oct 2026
-
Retirement Portfolio Diversification Example
22 Oct 2026
-
How to Rebalance a Multi Asset Portfolio
22 Oct 2026
-
How to Protect Investment Accounts From Fraud
22 Oct 2026
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026
-
How to Set Financial Goals That Build Wealth
20 Oct 2026
-
Robo Advisors Versus Brokers for Your Goals
20 Oct 2026
-
-
-
When Should Portfolios Rebalance for Growth?
08 Oct 2026
-
Platform Security Review for Confident Investors
08 Oct 2026
-
How to Invest Business Cash Reserves Wisely
08 Oct 2026
-
How to Calculate Compound Returns on Investments
08 Oct 2026
-
Alternative Assets Trends Reshaping Portfolios
08 Oct 2026
-
How to Read Portfolio Drawdowns With Confidence
06 Oct 2026