Robo Advisors Versus Brokers for Your Goals
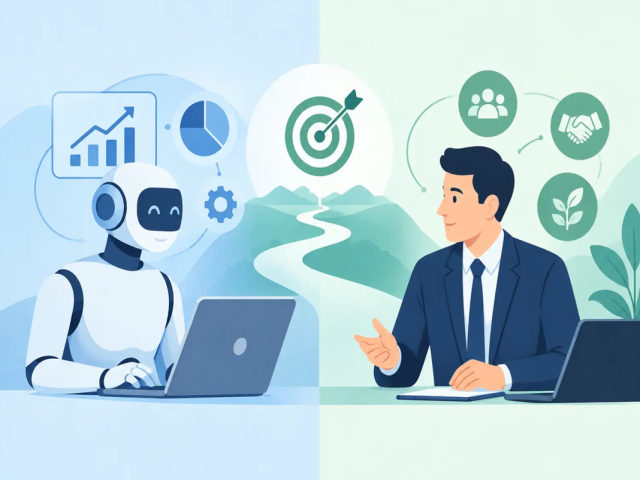
Robo advisors versus brokers: compare costs, control, guidance, and time commitment to choose an investing approach aligned with your financial goals.
The choice between robo advisors versus brokers is not simply about which app looks easier to use. It is about deciding how much of your financial future you want to manage personally, how much guidance you expect, and what you are willing to pay for support. For an investor focused on passive income and long-term wealth growth, the right choice can reduce stress while keeping your capital working toward clear goals.
A robo advisor can automate a large part of the investing process. A broker gives you the tools to make the decisions yourself. Neither is automatically better. The stronger fit depends on your time, confidence, portfolio size, and need for professional insight.
Robo Advisors Versus Brokers: The Core Difference
A robo advisor is a digital investment service that builds and manages a portfolio using algorithms. After you answer questions about your goals, time horizon, and comfort with risk, the platform generally assigns you to a diversified mix of investments. It may also automatically rebalance the portfolio when market movements change your target allocation.
A broker is a firm or platform that lets you buy and sell investments such as stocks, exchange-traded funds, bonds, options, mutual funds, and sometimes digital assets. With a self-directed brokerage account, you decide what to buy, when to trade, and when to sell. Some brokers also offer access to human financial professionals, managed accounts, research, and planning services.
The distinction matters: a robo advisor is designed around automated portfolio management, while a broker is designed around market access and investor choice. In practice, many robo advisors operate through brokerage accounts, which means the lines can overlap. What changes is who is making the day-to-day investment decisions.
When a Robo Advisor Makes Sense
Robo advisors appeal to people who want to invest consistently without turning investing into a second job. They are often a practical option for beginners, busy professionals, and anyone who knows they need a plan but does not want to analyze company earnings, follow interest-rate announcements, or rebalance a portfolio every quarter.
The largest benefit is discipline. When contributions are automated, money can move from your bank account into investments on a schedule. That can help reduce the temptation to wait for the “perfect” market moment, which often leads to missed opportunities. A portfolio based on your stated risk level may also prevent a common mistake: taking on more risk than you can emotionally handle during a market decline.
Robo advisors typically offer lower management costs than traditional full-service advisory relationships. Many use broadly diversified funds, making it easier to gain exposure to multiple sectors or global markets without selecting every holding individually. Some also provide tax-management features for eligible taxable accounts.
However, automation has limits. A robo advisor follows the framework it was built to follow. It may not fully account for a complex business ownership structure, a concentrated stock position from an employer, estate-planning needs, or a major life event that requires detailed judgment. The portfolio may be efficient, but it is not the same as having an experienced person deeply involved in your entire financial picture.
When a Broker Is the Better Fit
A broker is often the better choice when control is a priority. You can choose specific investments, set your own portfolio allocation, and make changes whenever your strategy or market view changes. For investors who enjoy research and understand the risks of active decision-making, that flexibility can be valuable.
Brokerage accounts also tend to offer a wider investment menu. Depending on the provider, you may access individual equities, fixed-income products, options strategies, international securities, funds, and other market opportunities. This can be useful if your goal is more specific than a standard diversified portfolio can provide.
A broker can also make sense for investors who want human guidance but do not want to hand over every decision. You may use professional research, speak with a representative, or pay for a managed account while retaining access to a broader set of investment choices.
The trade-off is responsibility. A self-directed broker account does not protect you from emotional decisions, unnecessary trading, or chasing a fast-moving trend. Low or zero trading commissions do not mean investing is free. Fund expenses, spreads, account fees, advisory fees, and taxes can all affect what you keep.
Cost Is More Than a Percentage
Comparing fees is essential, but the lowest advertised price is not always the lowest total cost. A robo advisor may charge an annual management fee, plus the internal expenses of the funds held in your portfolio. A broker may offer commission-free stock and ETF trades but charge for premium tools, certain fund transactions, options contracts, advice programs, or account services.
The bigger cost can be behavioral. An investor who pays a modest automated-management fee but stays invested according to a thoughtful plan may fare better than an investor who pays no trading commission and repeatedly buys high, sells low, or keeps excess cash on the sidelines.
At the same time, do not assume automated investing is always the most suitable answer. If your needs require tax strategy, retirement-income planning, insurance coordination, or business-related investment decisions, paying for qualified human advice can be worthwhile. Ask what service you are receiving, how the provider is compensated, and whether its recommendations are designed for your situation.
Control, Convenience, and Confidence
The real decision often comes down to three questions: Do you want control? Do you want convenience? Do you have confidence in your process?
If you want convenience, a robo advisor may be a strong starting point. You establish your objectives, fund the account, and let the system maintain the portfolio. This approach is particularly attractive when building wealth is important but daily market management is not how you want to spend your time.
If you want control, a broker provides direct access to the market. That freedom can support a customized strategy, but it requires consistency, education, and a clear understanding of risk. The market does not reward activity simply because it is activity.
Confidence should be earned, not assumed. A new investor may feel confident after reading a few market headlines, yet still lack a tested plan for volatility. On the other hand, an experienced investor may have a disciplined method that makes a self-directed brokerage account entirely appropriate. Your choice can change as your finances, knowledge, and goals evolve.
A Third Path: Professionally Managed Market Exposure
For some investors, the comparison is not strictly robo advisor or self-directed broker. They may prefer a managed investment service that combines technology with active market monitoring and professional execution. This approach can be appealing to people seeking exposure to equities, currencies, cryptocurrencies, indices, and commodities without personally placing every trade.
The appeal is straightforward: your capital is positioned to pursue market opportunities while you remain focused on work, family, or business. At Budrigantrade, this type of model is centered on managed market participation, portfolio visibility, and investment time horizons that can align with short-, mid-, or long-term objectives.
Still, managed does not mean risk-free. Global markets can move sharply, and no platform, analyst, algorithm, or strategy can guarantee a result. Before committing funds, understand the investment program, withdrawal terms, fees or profit-sharing arrangements, risk disclosures, asset exposure, and how performance is reported. Transparency should be a requirement, not a bonus.
How to Choose Without Overthinking It
Start with the outcome you want your money to support. A retirement goal 25 years away calls for a different approach than building a reserve for a home purchase in three years or seeking diversified exposure alongside an existing business income.
Next, be honest about your available time. If you will not consistently research investments, review allocations, and stay calm through volatility, a fully self-directed broker account may create more friction than freedom. If you enjoy that work and have a disciplined plan, the flexibility may be worth it.
Finally, consider the level of support that lets you act with confidence. Automation can create consistency. Human advice can provide context. Managed market exposure can reduce the operational burden. The best choice is the one you can understand, fund regularly, and stay committed to when markets become unpredictable.
Your investing approach should make financial progress feel more organized, not more overwhelming. Choose the level of control that supports your goals, then give your strategy the patience and attention it deserves.
Recent Posts
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026
-
How to Set Financial Goals That Build Wealth
20 Oct 2026
-
-
-
When Should Portfolios Rebalance for Growth?
08 Oct 2026
-
Platform Security Review for Confident Investors
08 Oct 2026
-
How to Invest Business Cash Reserves Wisely
08 Oct 2026
-
How to Calculate Compound Returns on Investments
08 Oct 2026
-
Alternative Assets Trends Reshaping Portfolios
08 Oct 2026
-
How to Read Portfolio Drawdowns With Confidence
06 Oct 2026
-
-
Are Investment Platforms Regulated in the US?
06 Oct 2026
-
How to Diversify Income Streams With Purpose
06 Oct 2026
-
Crypto Custody Service Review for Investors
06 Oct 2026
-
A Small Business Cash Reserve Example That Works
23 Sep 2026