How to Set Financial Goals That Build Wealth
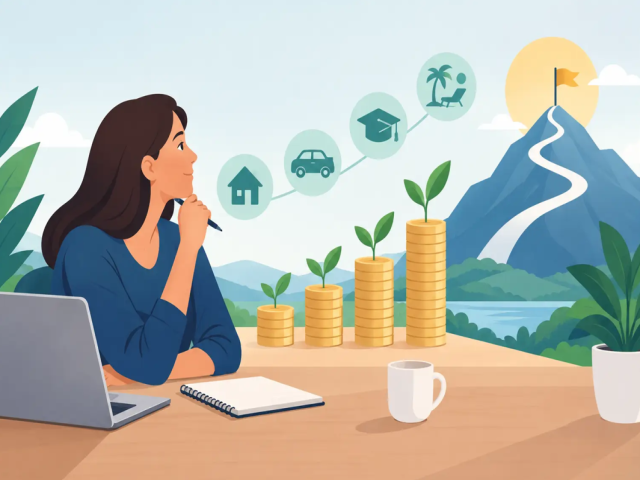
Learn how to set financial goals with clear timelines, realistic targets, and an investment plan built for income, security, and long-term growth today.
A paycheck can disappear quickly when every dollar arrives without a job. Rent, groceries, debt payments, family needs, and spontaneous expenses all compete for attention. Learning how to set financial goals gives your money direction, so your decisions support the life you want instead of simply responding to the next bill.
Financial goals are not reserved for high earners or experienced investors. They are practical targets that connect today’s income, savings, and investment choices to a future result: more security, a home purchase, a business reserve, passive income, or greater freedom over how you spend your time.
Start With the Future You Want to Fund
The strongest goals begin with a personal reason. “I want to save more” is a positive intention, but it is too broad to guide an action. “I want to build a $15,000 emergency reserve within 18 months” creates a clear destination and a way to measure progress.
Think about what financial well-being means in your own life. For one person, it may mean replacing reliance on credit cards. For another, it may mean generating supplementary income, funding a child’s education, protecting a business during slower months, or building long-term wealth through global market exposure.
Give yourself permission to want more than survival. A financial plan should cover immediate obligations, but it can also make room for opportunity. The key is separating urgent needs from meaningful ambitions, then assigning each one a realistic timeline.
How to Set Financial Goals With Clear Time Horizons
A useful financial goal has a specific amount, a deadline, and a purpose. It should also fit into one of three time horizons: short term, midterm, or long term. This distinction matters because money needed soon should be handled differently from money intended to grow over several years.
Short-term goals: the next 12 months
Short-term goals protect your day-to-day stability and help you avoid making expensive decisions under pressure. These may include building an emergency fund, paying down high-interest debt, saving for a move, covering insurance costs, or creating a cash reserve for a small business.
Keep short-term money accessible. The goal is reliability, not chasing the highest possible return. If a market investment declines just when you need to withdraw, a short-term plan can become a source of stress rather than security.
Midterm goals: one to five years
Midterm goals often include a down payment, a vehicle purchase, professional training, a wedding, business equipment, or capital for a planned venture. You may be able to take on more market exposure than with a short-term goal, but the closer the deadline gets, the more carefully you should manage risk.
For example, someone saving for a property purchase in four years might combine regular cash savings with a measured investment allocation. The right balance depends on how flexible the deadline is, how much market movement you can tolerate, and whether you have other funds available.
Long-term goals: five years and beyond
Long-term goals are where consistent investing can become especially powerful. Retirement, future passive income, legacy planning, and long-range wealth accumulation generally benefit from time because markets can move up and down in the short run.
A long horizon does not remove risk. It gives you more time to manage it. Diversification across asset types, disciplined contributions, and regular reviews can matter more than trying to predict every market move.
Turn Big Numbers Into Monthly Actions
Once you know the amount and deadline, calculate what the goal requires each month. This is the point where ambition becomes a plan.
If your target is $12,000 in two years, you need to set aside roughly $500 each month before accounting for any growth or returns. If $500 is not realistic, do not abandon the goal. Adjust one of the variables: extend the deadline, reduce the target, increase income, cut a recurring expense, or use a combination of these options.
Be honest about your starting point. A goal that requires every spare dollar can fail the first time an unexpected expense appears. Build a small margin into your plan, particularly if income changes from month to month.
Automation can make consistency easier. Schedule transfers after payday so saving and investing happen before discretionary spending takes over. For investors who prefer managed market participation rather than daily trading, a recurring contribution can also create discipline without requiring constant attention to price charts or headlines.
Match Your Investment Strategy to the Goal
Not every dollar should be invested the same way. Your time horizon, risk tolerance, liquidity needs, and existing financial responsibilities should shape the approach.
A person with limited savings may need to prioritize an emergency reserve before allocating heavily to market-based investments. Someone with stable income, adequate cash reserves, and a long-term goal may be more comfortable seeking growth through a diversified investment strategy. Neither choice is automatically better. The right choice depends on the job that money needs to do.
Managed investment services can appeal to people who want exposure to equities, currencies, cryptocurrencies, indices, or commodities without personally monitoring markets every day. Professional analysis and active monitoring may save time, but they do not eliminate market risk or guarantee a profit. Review how a platform handles transparency, withdrawals, fees, risk disclosures, and portfolio visibility before committing funds.
At Budrigantrade, the idea is to make broader market participation more accessible for people who want a managed approach to pursuing growth and passive-income opportunities. Even with a managed strategy, investors should understand their time horizon and avoid placing money needed for immediate expenses into investments that can fluctuate.
Prioritize Goals Without Losing Momentum
Most people have more than one financial goal at a time. Trying to fund all of them equally can make progress feel slow, especially at the beginning. Prioritization helps you direct resources where they will have the greatest effect.
Start with financial stability. High-interest debt, overdue essentials, and a complete lack of emergency savings can undermine every other goal. Once your foundation is stronger, divide available funds between a near-term priority and a longer-term wealth goal.
A simple structure may look like this: protect your cash flow first, contribute consistently toward the next major purchase, and maintain an automatic contribution toward long-term investments. This lets you make visible progress now while still building for later.
Do not confuse urgency with importance. A sale, social event, or trending investment may feel urgent, but it may not move you closer to your stated goals. A written plan makes it easier to say no to distractions without feeling deprived.
Review Your Goals When Life Changes
Financial goals should be firm enough to guide you and flexible enough to survive real life. A promotion, job loss, marriage, new child, medical bill, relocation, or change in business revenue can all require a reset.
Review your goals at least every quarter. Check your current balances, contributions, debt, spending patterns, and investment performance. Ask whether the deadline still makes sense and whether your risk level still matches your circumstances.
Avoid changing direction because of every short-term market headline. A review is meant to improve your plan, not encourage emotional decisions. If a goal remains important, small adjustments and consistent action often produce better results than dramatic moves.
Make Progress Visible
Motivation grows when progress is easy to see. Track your goal amount, current balance, monthly contribution, and deadline in one simple place. A percentage can be especially encouraging: reaching 20% or 50% of a target feels more meaningful than staring at a distant final number.
Celebrate milestones without undoing them. When you pay off a debt or reach a savings target, redirect at least part of the freed-up money toward the next goal. This is how financial progress compounds: not only through potential investment returns, but through better habits and smarter use of every new dollar.
Your first goal does not have to be perfect. Choose one target that would genuinely improve your financial life, assign it a number and a date, then make the first contribution. Clarity creates momentum, and momentum can turn a future you hope for into one you are actively funding.
Recent Posts
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026
-
Robo Advisors Versus Brokers for Your Goals
20 Oct 2026
-
-
-
When Should Portfolios Rebalance for Growth?
08 Oct 2026
-
Platform Security Review for Confident Investors
08 Oct 2026
-
How to Invest Business Cash Reserves Wisely
08 Oct 2026
-
How to Calculate Compound Returns on Investments
08 Oct 2026
-
Alternative Assets Trends Reshaping Portfolios
08 Oct 2026
-
How to Read Portfolio Drawdowns With Confidence
06 Oct 2026
-
-
Are Investment Platforms Regulated in the US?
06 Oct 2026
-
How to Diversify Income Streams With Purpose
06 Oct 2026
-
Crypto Custody Service Review for Investors
06 Oct 2026
-
A Small Business Cash Reserve Example That Works
23 Sep 2026