How to Rebalance a Multi Asset Portfolio
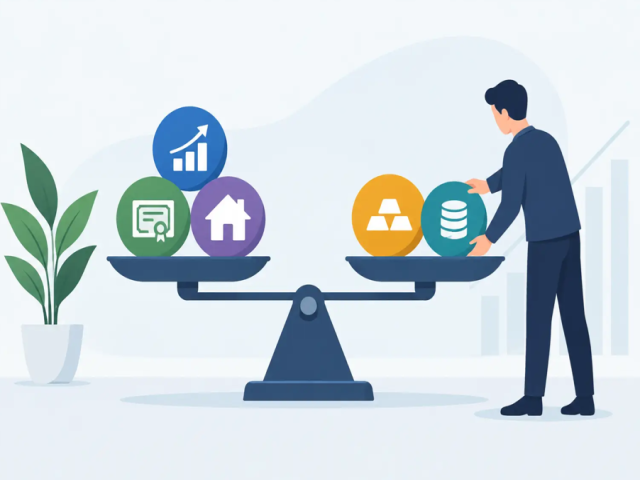
Learn how to rebalance a multi asset portfolio with clear targets, practical timing, and disciplined decisions that support long-term financial goals.
A portfolio can look healthy on paper while quietly taking on more risk than you intended. A strong stock rally, a crypto surge, or a sharp move in commodities can shift your original mix within months. Learning how to rebalance a multi asset portfolio gives you a disciplined way to bring your investments back in line with your financial goals - without relying on emotion or chasing the latest market move.
For investors seeking passive income and long-term growth, rebalancing is not about predicting tomorrow’s winning asset. It is about protecting the strategy you chose before market excitement, fear, and headlines had a chance to influence it.
What It Means to Rebalance a Multi Asset Portfolio
A multi-asset portfolio holds capital across more than one investment category. That may include equities, currencies, cryptocurrencies, indices, commodities, and cash or cash-equivalent positions. Each category responds differently to inflation, interest rates, economic growth, geopolitical events, and changes in investor confidence.
Rebalancing means comparing your current holdings with your target allocation, then making adjustments to restore the intended mix. If your target is 50% equities, 20% indices, 15% commodities, 10% crypto, and 5% cash, market performance will eventually move those numbers. Equities may rise until they represent 62% of the portfolio, while commodities and cash become smaller portions.
At that point, your portfolio is no longer carrying the same level or type of risk you originally accepted. Rebalancing might mean directing new funds toward underweight assets, reducing part of an overweight position, or doing both.
The goal is not to sell every investment that has performed well. The goal is to prevent one successful area of the market from taking too much control over your financial future.
Why Portfolio Drift Can Affect Your Financial Plan
Portfolio drift happens naturally. It is the result of markets doing what markets do: moving at different speeds and in different directions. A diversified allocation that was carefully built at the beginning of the year may become heavily concentrated by year-end.
That concentration can create unexpected pressure. If one asset class has grown well beyond its target allocation and then declines sharply, the portfolio may experience a larger loss than you were prepared to accept. Investors often discover this only after volatility arrives.
Rebalancing creates a repeatable response. Instead of making decisions based on whether an asset feels exciting or disappointing, you use predetermined percentages and a clear process. This can reduce impulsive trading, especially during volatile periods in crypto, currency, and equity markets.
It also encourages a behavior many investors find difficult: taking some profit from assets that have risen significantly and adding measured exposure to areas that have lagged. That does not guarantee returns. It does, however, keep risk aligned with the structure designed for your timeline and objectives.
Start With a Clear Target Allocation
Before you can rebalance, you need a target. Your target allocation should reflect what you want your capital to do, how long you can keep it invested, and how much market movement you can realistically tolerate.
An investor building long-term wealth may accept greater equity and index exposure because there is more time to recover from market downturns. Someone focused on near-term income or a major purchase may prefer a larger allocation to cash-like holdings or lower-volatility assets. A business entity managing reserves may have a different priority again: preserving access to capital while still pursuing measured growth.
There is no universal “best” allocation. A portfolio with higher crypto or commodity exposure may offer meaningful opportunity, but it can also experience sharp price swings. A more conservative allocation may feel steadier, but it may not grow as quickly during a strong risk-on market.
Write the percentages down. Without a documented target, it becomes too easy to redefine your strategy every time prices move.
Use Bands Rather Than Reacting to Every Move
Rebalancing every time an asset changes by a fraction of a percent can create unnecessary transactions and turn a long-term plan into constant activity. A more practical approach is to use tolerance bands.
For example, you might decide to rebalance when an asset class moves 5 percentage points away from its target. If crypto has a 10% target, you may take action when it rises above 15% or falls below 5%. The right band depends on the asset’s volatility, your portfolio size, transaction costs, and how closely you want to control risk.
Highly volatile assets may require closer attention. Less volatile allocations may only need periodic review. The point is to choose the rule before a market move tests your discipline.
How Often Should You Review Your Allocation?
For many investors, a quarterly review is a sensible starting point. It is frequent enough to identify meaningful changes but not so frequent that normal market noise demands action. Semiannual or annual rebalancing can also work for portfolios built around longer-term objectives.
Time-based reviews are simple, but threshold-based reviews can be more responsive. You might inspect the portfolio every quarter while only making changes when a holding exceeds its permitted band. This combination offers structure without forcing trades that do not serve your strategy.
There are moments when a review deserves more urgency. A major life event, a change in income, a planned withdrawal, or a shift in your investment horizon can all justify revisiting the target allocation. The portfolio should support your life, not become a fixed rule that ignores it.
Practical Ways to Rebalance a Multi Asset Portfolio
The most direct method is selling a portion of overweight assets and buying underweight assets. If equities have grown beyond their target and commodities have fallen below theirs, you can reduce some equity exposure and add to commodities. This is effective, but investors should consider possible taxes, spreads, and transaction costs before acting.
A second method is using new deposits. Rather than selling a winning position, direct fresh capital toward the assets that are below target. This can be especially useful for investors making regular contributions, because it restores balance gradually while avoiding unnecessary sales.
A third option is to use distributions, dividends, realized profits, or available cash to strengthen underweight areas. This approach can be efficient when the portfolio already generates cash flow or when you want to maintain core positions.
In practice, the best method often combines all three. New contributions may handle small allocation gaps, while larger drift may require selective trimming. The decision depends on the size of the imbalance and the costs of correcting it.
Avoid These Common Rebalancing Mistakes
The biggest mistake is treating rebalancing as a prediction tool. Reducing an asset after it rises does not mean you believe it will fall tomorrow. Adding to an underweight asset does not mean you expect an immediate rebound. You are managing exposure, not making a short-term forecast.
Another mistake is ignoring fees and taxes. A portfolio can be perfectly balanced but less efficient if frequent selling creates costs that outweigh the benefit of small adjustments. Tax treatment varies by account type, holding period, location, and investor circumstances, so professional tax guidance may be appropriate before large changes.
Investors also sometimes rebalance into assets they no longer understand or no longer want to own. If your view of an asset class has genuinely changed because your goals changed, revisit the entire target allocation first. Do not blindly restore an outdated plan.
Finally, do not confuse visible activity with progress. A disciplined portfolio does not need constant trading to be actively managed. Sometimes the best decision is to review the numbers, confirm they remain within range, and leave the allocation alone.
Rebalancing With Managed Market Exposure
Managing several global markets can demand more attention than most working professionals want to give. Equities may move on earnings data, currencies on central-bank decisions, commodities on supply changes, and crypto around the clock. That is why some investors choose managed exposure rather than handling each adjustment personally.
At Budrigantrade, multi-market participation is designed to give investors visibility into their capital while professional market monitoring and trading execution handle the day-to-day complexity. A managed approach can make it easier to pursue diversification without needing to watch every chart, news release, or overnight price movement.
Still, convenience should not replace clarity. Ask how your capital is allocated, what risks are involved, how performance is reported, and when funds can be accessed. Transparent information helps you make decisions with confidence and keeps your investment plan connected to your actual financial priorities.
Make Rebalancing Part of Your Routine
Set a review date, define your target ranges, and decide in advance what will trigger an adjustment. Keep the process simple enough that you will follow it during both strong markets and difficult ones. Your financial well-being is not built by reacting perfectly to every price move. It is built by maintaining a strategy that can keep working when markets refuse to be predictable.
A balanced portfolio will never eliminate risk, and no allocation can promise a profit. But a clear rebalancing process can keep your capital focused on the opportunities you chose, rather than the market noise you did not plan for.
Recent Posts
-
Guide to Economic Indicators for Investors
22 Oct 2026
-
Retirement Portfolio Diversification Example
22 Oct 2026
-
When Portfolios Rebalance and Why It Matters
22 Oct 2026
-
How to Protect Investment Accounts From Fraud
22 Oct 2026
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026
-
How to Set Financial Goals That Build Wealth
20 Oct 2026
-
Robo Advisors Versus Brokers for Your Goals
20 Oct 2026
-
-
-
When Should Portfolios Rebalance for Growth?
08 Oct 2026
-
Platform Security Review for Confident Investors
08 Oct 2026
-
How to Invest Business Cash Reserves Wisely
08 Oct 2026
-
How to Calculate Compound Returns on Investments
08 Oct 2026
-
Alternative Assets Trends Reshaping Portfolios
08 Oct 2026
-
How to Read Portfolio Drawdowns With Confidence
06 Oct 2026