High Yield Savings Versus Investing: Which Fits?
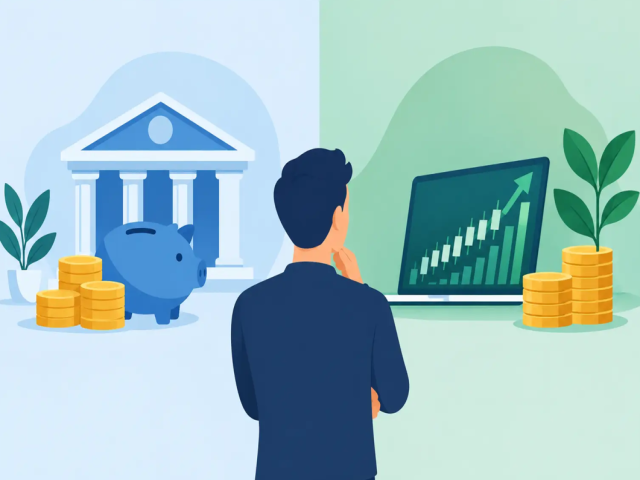
High yield savings versus investing: compare safety, access, growth potential, and time horizons to put each dollar toward the right financial goal today.
A $10,000 balance can serve two very different jobs. It can protect your ability to handle an emergency, move house, or seize a business opportunity. Or it can become capital designed to grow over years. That is the real question behind high yield savings versus investing: not which option is universally better, but what you need your money to do next.
High-yield savings accounts offer stability and fast access. Investing offers a greater potential for long-term growth, along with a real possibility of short-term losses. A confident financial plan often uses both - with each dollar assigned to a purpose rather than left sitting without direction.
High Yield Savings Versus Investing at a Glance
A high-yield savings account is a cash account that pays interest at a rate typically higher than a traditional savings account. Its central benefit is predictability. Your account balance does not fluctuate with stock prices, and you can generally access your funds quickly. In the United States, deposits at an FDIC-insured bank are protected up to applicable insurance limits.
Investing puts money into assets such as stocks, bonds, funds, real estate, commodities, or other market opportunities. The objective is to earn returns through price appreciation, income, or both. Unlike a savings account, investment values can rise and fall. That volatility is the price investors may pay for the possibility of building more purchasing power over time.
The distinction matters because money needed soon should not be exposed to avoidable market risk. At the same time, money that will not be needed for many years may lose ground to inflation if it remains entirely in cash.
When a High-Yield Savings Account Makes More Sense
Cash is not a failure to invest. It is a strategic reserve. A high-yield savings account is usually a strong fit for money with a short deadline or a non-negotiable purpose.
Your emergency fund belongs in this category. If your income changes, your car needs repair, or an unexpected medical bill arrives, the priority is access - not chasing a return that could disappear during a market decline. Many people aim to hold several months of essential expenses in readily available savings, though the right amount depends on income stability, dependents, debt obligations, and insurance coverage.
Savings can also make sense for a planned purchase within the next one to three years. A down payment, tuition payment, wedding budget, tax bill, business expense, or relocation fund should not depend on whether markets have a good quarter. When the date matters more than the growth potential, protecting principal is often the smarter decision.
There are trade-offs. Savings rates can change, and a higher rate today is not a lifetime guarantee. Interest income may also be taxable. Most significantly, cash can lose real buying power if inflation outpaces the interest you earn. A savings account protects the dollar amount, but it may not protect what those dollars can buy years from now.
When Investing Has the Stronger Role
Investing is built for goals that need time to develop. Retirement, long-term family wealth, future education funding, and capital intended to compound over five years or more are common examples.
Market investments have historically offered greater long-term return potential than cash, but history is not a promise. There can be difficult months, sharp declines, and periods when a portfolio takes time to recover. The key advantage is not a guaranteed outcome. It is the opportunity to participate in the growth and income produced by a diversified set of assets over a longer horizon.
Time changes the equation. If you do not need to withdraw funds during a downturn, you may be able to remain invested rather than sell at an unfavorable price. That patience can matter far more than trying to predict every market move.
A managed investment approach may appeal to people who want exposure to global opportunities without handling day-to-day trading. Rather than reacting to headlines or monitoring charts after work, investors can choose a strategy aligned with their risk tolerance and timeline while professionals oversee execution. At Budrigantrade, that approach centers on managed market exposure across asset classes for investors seeking a more hands-off path to participation.
Professional management can offer convenience and structured decision-making, but it does not remove risk. Before committing capital, understand the investment strategy, withdrawal terms, charges, liquidity conditions, and the possibility of loss. Transparency is not a bonus feature in investing. It is part of making an informed decision.
The Question That Decides Most of the Debate: When Will You Need the Money?
The simplest way to compare high-yield savings versus investing is to begin with your timeline.
If you may need the money within a year, savings is generally the more suitable home. The closer you are to needing the funds, the less room you have to wait out volatility. A market drop at the wrong time can turn a planned purchase into an unwanted delay.
For goals roughly one to five years away, the answer depends on flexibility. If the deadline is fixed and the funds are essential, lean more heavily toward cash or lower-volatility options. If the goal date can move and you can tolerate changes in value, a carefully considered investment allocation may have a role.
For goals more than five years away, investing often becomes more compelling. That does not mean putting every dollar into high-risk assets. It means giving long-term capital a reasonable chance to grow rather than treating it like money you need next month.
Risk Tolerance Is More Than a Questionnaire
Two people with the same income can make different choices for good reasons. One may have a stable salary, no high-interest debt, and a strong emergency reserve. Another may be self-employed, supporting family members, or preparing for a major purchase. Their capacity to take risk is different, even if both describe themselves as ambitious investors.
Your emotional response to losses also matters. A portfolio that looks attractive on paper is not useful if a 15% decline causes you to withdraw in panic. The right level of risk is one you can financially and psychologically sustain.
Ask yourself three direct questions: Could I leave this money untouched for several years? Could I handle a decline without selling? Have I already protected my near-term needs? If the answer to any is no, build your savings foundation first.
A Practical Way to Use Both
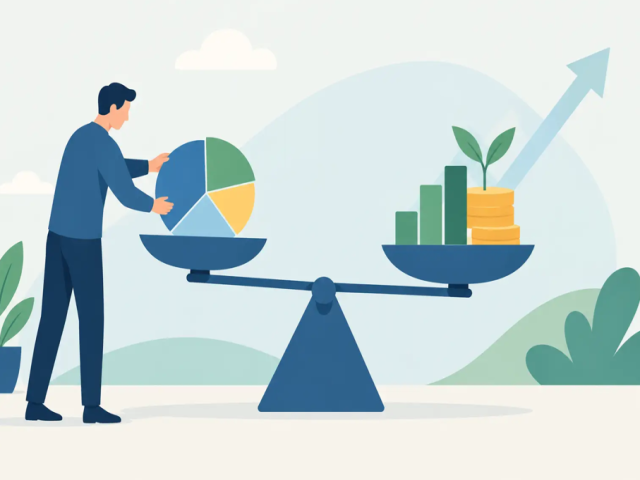
For many investors, the choice is not savings or investing. It is savings for security and investing for advancement.
Start by protecting essential cash needs. Then direct surplus money based on its purpose. For example, money for a home repair fund can stay in a high-yield savings account, while a separate monthly contribution can go toward a long-term investment strategy. Keeping these goals in separate accounts or categories makes it easier to avoid spending investment capital on short-term surprises.
Automation can make the plan easier to maintain. A scheduled transfer to savings builds your reserve without repeated decisions. A recurring investment contribution creates consistency, which can be valuable when markets are uncertain. The amount matters less at first than creating a habit you can maintain through changing market conditions.
Do not overlook expensive debt. Credit card balances and other high-interest obligations can undermine both saving and investing progress. In many cases, reducing that burden delivers a more dependable improvement to your financial position than taking additional market risk.
Avoid the Common Comparison Mistakes
The first mistake is comparing a savings rate with an investment return as if they offer the same experience. They do not. Savings interest is generally designed for stability and liquidity. Investment returns are uncertain and can include periods of loss. A higher projected return is meaningful only when you understand the risk required to pursue it.
The second mistake is leaving every dollar in savings because investing feels intimidating. Caution has value, but excessive caution can create a different risk: failing to build enough future purchasing power. Learning your options and starting with an amount appropriate for your circumstances can be more productive than waiting for perfect confidence.
The third mistake is investing emergency money because recent returns look exciting. Market enthusiasm can reverse quickly. Your emergency fund should be boring by design. Its job is to give you choices when life is not predictable.
Choose a Job for Every Dollar
The strongest financial decisions rarely come from chasing the highest number on a screen. They come from matching each dollar to the job it must perform. Keep your short-term security accessible, give long-term capital time to pursue growth, and review the balance as your income, goals, and responsibilities change.
A well-built plan gives you more than a return target. It gives you the confidence to handle what is next without forcing every financial goal to carry the same risk.
Recent Posts
-
-
Liquidity Planning for Investors That Works
26 Oct 2026
-
Can Entities Invest? A Practical Path to Growth
26 Oct 2026
-
-
Guide to Economic Indicators for Investors
22 Oct 2026
-
Retirement Portfolio Diversification Example
22 Oct 2026
-
When Portfolios Rebalance and Why It Matters
22 Oct 2026
-
How to Rebalance a Multi Asset Portfolio
22 Oct 2026
-
How to Protect Investment Accounts From Fraud
22 Oct 2026
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026
-
How to Set Financial Goals That Build Wealth
20 Oct 2026
-
Robo Advisors Versus Brokers for Your Goals
20 Oct 2026
-
-
-
When Should Portfolios Rebalance for Growth?
08 Oct 2026