Financial Regulation: What Investors Should Check
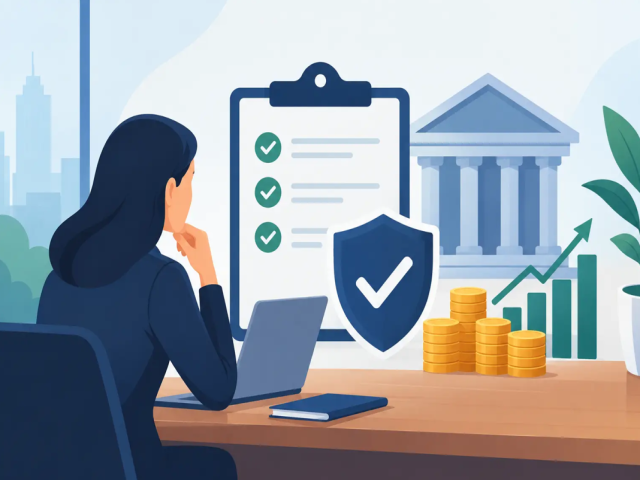
Financial regulation shapes how investment firms handle client money, disclosures, and risk. Learn what to review before you fund an online account safely.
A polished website, a promising return target, and an easy deposit process can make an investment opportunity feel ready to trust. Financial regulation is the layer that asks harder questions: Who oversees the business? What is it authorized to do? How is client money handled? What information must be disclosed before an investor commits funds?
For investors pursuing passive income through managed market exposure, those questions are not administrative details. They are part of protecting capital. A platform may provide access to equities, currencies, crypto assets, indices, or commodities, but the level of oversight, the rules that apply, and the investor protections available can differ widely by product and jurisdiction.
What Financial Regulation Is Designed to Do
Financial regulation is the framework of laws, licensing rules, reporting obligations, and conduct standards that governs financial services. Its purpose is not to eliminate investment risk. Markets can move sharply, trades can lose value, and no legitimate framework can guarantee a profit. Regulation is meant to make the relationship between investor and provider more accountable, transparent, and fair.
In practice, regulators may require firms to identify clients, maintain records, publish material disclosures, protect personal data, prevent money laundering, manage conflicts of interest, and communicate honestly about risk. Depending on the service offered, a firm may also need registration or authorization to advise clients, manage assets, broker transactions, custody assets, or offer securities.
That distinction matters. A company can be properly registered as a business without being licensed to provide every type of financial service. Business incorporation and financial authorization are not the same thing. Investors should understand which legal entity they are dealing with, where it operates, and what activity it is permitted to carry out.
Why Regulation Matters for Managed Investing
Managed investing is built on delegation. Instead of monitoring charts, studying economic releases, and placing trades yourself, you entrust decisions or execution to a platform, manager, or trading team. That can save time and give investors exposure to strategies they would not manage alone. It also creates an additional responsibility: evaluating the provider, not only the markets.
A regulated operating environment can set expectations around how a provider presents opportunities and handles customer relationships. Clear rules may govern marketing statements, complaint handling, client onboarding, risk notices, and the separation of company operations from client assets. The exact protections depend on the country, the financial product, and the regulator involved.
For example, investment services offered to US residents may be subject to different requirements than services offered internationally. Crypto-related products can be governed differently from traditional securities or foreign exchange services. Commodity and derivatives activity can involve another category of rules. There is no single global badge that covers every service in every location.
This is why a serious investor avoids broad assumptions. Seeing words such as “registered,” “verified,” or “compliant” is not enough on its own. The useful question is: registered or regulated by whom, for what service, and in which jurisdiction?
The Checks to Make Before Funding an Account
You do not need to be a lawyer or professional trader to perform basic due diligence. A few disciplined checks can help you distinguish clear information from vague reassurance.
Start by identifying the legal name of the company and its stated country of operation. Reputable financial businesses should make it possible to understand who provides the service. If a platform uses several brands, payment processors, or corporate entities, ask which entity holds your agreement and receives your funds.
Next, review the terms that describe the investment arrangement. Are you purchasing an asset, opening a trading account, participating in a managed strategy, lending funds, or entering another type of agreement? The answer affects your rights, potential returns, liquidity, and risk. It also affects which regulations may apply.
Then look closely at how deposits, withdrawals, fees, and profit calculations work. Convenience features such as automated funding, crypto deposits, and fast withdrawal requests can be valuable, but they should not replace clarity. You should know the accepted payment method, applicable charges, expected processing times, withdrawal conditions, and whether there are limits or verification steps.
A practical review should include these five points:
- The provider’s legal entity, operating address, and contact channels
- The regulator or licensing authority claimed, along with the type of authorization
- The investment agreement, including fees, withdrawal terms, and risk disclosures
- The custody or payment process used for deposits and withdrawals
- The procedure for support requests, disputes, and formal complaints
If the information is incomplete, contradictory, or difficult to obtain, pause before transferring money. Pressure to deposit immediately is not a substitute for documentation. An opportunity worth considering should allow room for informed decision-making.
Risk Disclosures Are Not Fine Print
Many people skim risk disclosures because the language can feel cautious or technical. Yet those pages often reveal the practical limits of an investment program. They explain whether returns are variable, whether capital can decline, whether withdrawals are subject to timing conditions, and whether certain market events can affect access to funds.
For managed portfolios, past performance should be treated as information, not a promise. A strategy that performed well in a favorable market may experience a different result when interest rates, liquidity, volatility, or currency conditions change. This is especially true for portfolios that include high-volatility assets such as cryptocurrencies, leveraged instruments, or certain foreign exchange positions.
The most useful providers explain opportunity and risk together. They can describe how their analysts monitor markets, how strategies are selected, and how clients can view account activity, while still being direct about uncertainty. Strong messaging should never imply that professional management removes the possibility of loss.
Your personal time horizon matters as well. Funds needed for rent, payroll, emergency expenses, or a near-term purchase should not be exposed to risks that you cannot afford to carry. Short-term income goals, medium-term plans, and long-term wealth building require different levels of liquidity and tolerance for market movement.
Transparency Should Be Easy to Verify
Transparency is more than a dashboard showing a balance. It means investors can understand what they are participating in and can ask meaningful questions about it. Account visibility is valuable when it is supported by plain explanations of performance calculations, fees, account status, and transaction history.
For a managed investment service, ask how gains and losses are calculated, when a performance fee is charged, and whether the fee is based on realized profits or another method. If a provider charges a share of profit, investors should be able to see how that share is determined and when it is deducted.
It is also reasonable to ask how risk is approached. No investment team should be expected to reveal every trading decision in real time, but it should be able to explain its broad market focus, portfolio time frames, and the type of controls used to manage exposure. General language about “advanced strategies” carries less weight than clear information that an investor can evaluate.
For platforms offering digital-asset funding, security questions deserve extra attention. Understand whether the transaction is irreversible, which wallet or payment details are official, how account access is protected, and what verification steps apply to withdrawals. Never send funds based solely on a message from social media, email, or a private chat. Confirm instructions through the platform’s official account area and established support process.
Financial Regulation and Your Role as an Investor
Regulation can improve standards, but it cannot make every investment suitable for every person. Investors still need to decide how much capital they can commit, what level of volatility they can accept, and whether the opportunity fits their broader financial plan.
A balanced approach can be more productive than chasing the highest advertised return. Consider diversification across assets and time horizons. Keep an emergency reserve outside of market-based investments. Avoid committing money you need on a fixed date. If an investment arrangement is unfamiliar, begin with an amount that allows you to learn the process without placing your financial well-being under pressure.
For individuals and businesses alike, documentation is part of disciplined investing. Save account agreements, deposit confirmations, withdrawal records, fee statements, and communications with support. These records help you track performance and make clearer decisions over time.
The best investment experience combines access with accountability. Whether you are seeking passive income, building long-term capital, or putting idle business funds to work, let financial regulation guide your questions before your money moves. A provider that values trust should welcome informed investors, communicate plainly, and give you the space to decide with confidence.
Recent Posts
-
Liquidity Planning for Investors That Works
26 Oct 2026
-
Can Entities Invest? A Practical Path to Growth
26 Oct 2026
-
-
High Yield Savings Versus Investing: Which Fits?
26 Oct 2026
-
Guide to Economic Indicators for Investors
22 Oct 2026
-
Retirement Portfolio Diversification Example
22 Oct 2026
-
When Portfolios Rebalance and Why It Matters
22 Oct 2026
-
How to Rebalance a Multi Asset Portfolio
22 Oct 2026
-
How to Protect Investment Accounts From Fraud
22 Oct 2026
-
What Is Investment Liquidity and Why It Matters
20 Oct 2026
-
How to Set Financial Goals That Build Wealth
20 Oct 2026
-
Robo Advisors Versus Brokers for Your Goals
20 Oct 2026
-
-
-
When Should Portfolios Rebalance for Growth?
08 Oct 2026